The 7 Best Lenders for a Personal Loan After Bankruptcy in 2026

Personal loan after bankruptcy

The 7 Best Lenders for a Personal Loan After Bankruptcy in 2026

Last updated: 2026-10-16

Trying to fix your finances after a bankruptcy can feel like walking through a thick fog. You might need a quick car repair to get to work, or perhaps an unexpected medical bill popped up right after your discharge. Sometimes, it is just about bridging a gap caused by a sudden change in employment. The goal is to find a lender who sees your current potential instead of just your past mistakes.

The way people borrow money has changed a lot. Where a bankruptcy once acted as a permanent “no,” modern fintech companies and community institutions are looking at your recent behavior. They care about the trajectory of your finances today rather than just the scars left on your credit report from years ago. It is about where you are going, not just where you have been.

Picking the right lender involves more than just glancing at an interest rate. You have to weigh how fast you can get the cash, what the minimum requirements are, and how much flexibility the company offers. Some providers focus on rapid cash for emergencies, while others offer structured installment plans to help you rebuild your credit over time. It is a balancing act between speed and long-term stability.

Accessibility is a tricky term that does not mean the same thing to everyone. A lender that is incredibly easy to get approved with might charge a premium for that convenience. On the other hand, a lender with stricter rules might offer the lower rates you need for long-term debt management. You have to decide whether you need a quick fix or a long-term strategy.

  1. FastLendGo
  2. SoFi
  3. Prosper
  4. Avant
  5. Allegiance Credit Union
  6. VivaLoan
  7. World Finance

Evaluating Lenders for Post-Bankruptcy Borrowing

This ranking focuses heavily on how easy it is to get approved and how fast you see the money. Financial emergencies do not wait for a perfect credit score to resolve themselves. We prioritized lenders that provide clear paths for people with different credit histories. If a delay of three days means you lose your utility service, you need a lender that moves quickly.

We also looked at the variety of loan amounts available. A lender that only offers tiny microloans might not help if you need to consolidate debt or fix a roof. Conversely, traditional banks often have massive hurdles, requiring collateral or credit scores that a post-bankruptcy borrower simply cannot reach yet. We looked for “soft” credit pulls so you can shop around without hurting your score.

Lender Name Loan Amounts Funding Speed Credit Requirements
FastLendGo $500 – $5,000+ Quick access Bad/Fair/Good/Great
SoFi see site see site see site
Prosper $2,000 – $50,000 Fast access see site
Avant see site see site see site
Allegiance Credit Union see site see site see site
VivaLoan $100 – $15,000 As soon as tomorrow All credit types welcome
World Finance see site see site see site

The Top Ranked Lenders for Rebuilding Credit

1. FastLendGo
FastLendGo – fastlendgo.com

FastLendGo is a great option for anyone stuck in a tight spot. They offer a wide range of options, from small $500 loans to larger $5,000 packages. This flexibility is helpful if you are juggling several different needs, like a small repair for a car and a larger bill for your taxes.

The whole platform is built for speed, which is perfect if you need cash immediately. Whether you are dealing with dental bills, auto repairs, or home maintenance, they make it easy to compare local options. Traditional banks often require mountains of paperwork and multiple trips, but FastLendGo uses a digital-first approach to get things moving quickly.

It is a solid choice for a quick fix when you cannot afford to wait around for a long approval process.

Pros:

  • Wide variety of loan amounts from $500 to $5,000 and beyond.
  • Covers specific needs like auto, dental, and roof financing.
  • Accommodates various credit tiers from bad to great.

Cons:

  • May not offer the lowest rates for those with excellent credit.

2. SoFi
SoFi – sofi.com

SoFi works more like a complete financial ecosystem. While many know them for banking and investments, they offer sophisticated tools to help manage your money. Their high-yield savings accounts can help you start rebuilding your savings effectively, giving you a safe place to park cash while your credit score climbs.

By automating your savings through their platform, you can build a buffer that helps you avoid high-interest debt in the future. This lender is perfect for the person who wants to manage everything in a single place, from checking accounts to mortgages.

They are more selective than the micro-lenders, but their products are built for people who have moved past their hardest financial struggles. It is a polished option if you are looking toward long-term stability and wealth growth.

Pros:

  • Integrated banking, investing, and insurance services.
  • High APY options for savings accounts.
  • User-friendly digital platform.

Cons:

  • Typically requires a higher credit tier for the best terms.

3. Prosper
Prosper – prosper.com

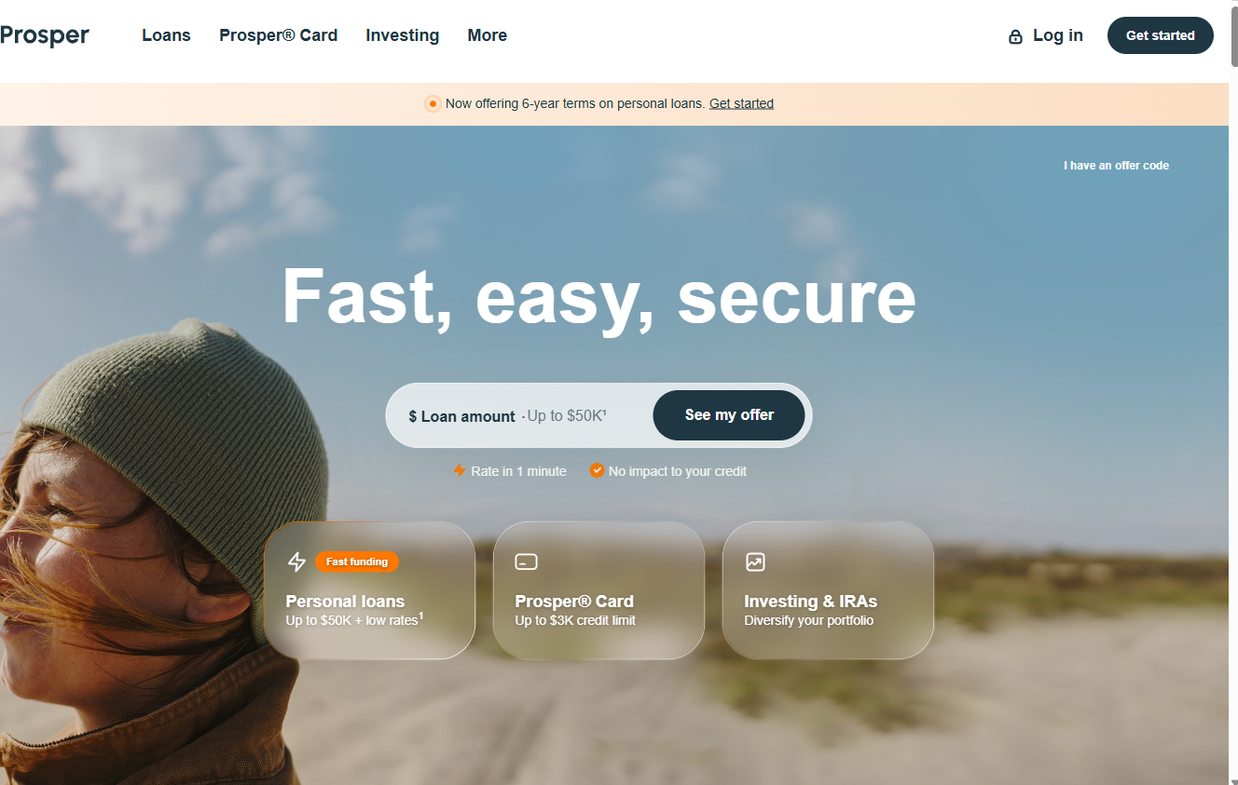
Prosper gives you a look into peer-to-peer (P2P) lending. They provide substantial amounts, ranging from $2,000 up to $50,000. This makes them a heavy hitter if you need to tackle major debt or large expenses like tuition or home renovations. Because they rely on individual investors rather than a bank’s pool of money, their criteria can be different from traditional lenders.

Their platform is fast and secure. You can see your rates in about a minute through a soft credit pull. This is vital if you are worried about hurting your credit score while you are just shopping around for the best deal.

For anyone wanting to move away from standard bank loans, Prosper offers an efficient experience. It is a strong choice for large-scale financing when a traditional bank might have given you a hard no.

Pros:

  • High loan ceilings up to $50,000.
  • Quick rate checking with minimal impact to credit.
  • Fast and secure online application process.

Cons:

  • Peer-to-peer models can sometimes have variable approval rates based on investor demand.

4. Avant
Avant – avant.com

Avant focuses on helping you move your financial life forward. They offer solutions like credit cards and installment loans, which are great for proving you can make consistent, on-time payments. Their approach feels more like a partnership, providing tools to help you reach specific goals like debt consolidation.

Whether you need to combine several high-interest payments into one manageable monthly bill or you just need an emergency loan for a sudden crisis, Avant has options. They aim to provide clear answers to difficult financial questions.

Their model is tuned for the middle-ground borrower. These are people who might not have elite scores but have shown steady income and responsibility through their recent financial history.

Pros:

  • Specializes in debt consolidation and emergency loans.
  • Flexible solutions for different life stages.
  • User-focused support and tools.

Cons:

  • Specific eligibility criteria can be difficult to navigate.

5. Allegiance Credit Union
Allegiance Credit Union – allegiancecu.com

Allegiance Credit Union is a community-focused institution that has been around since 1963. They operate under the idea that every story matters, including those of people rebuilding after a setback. This approach is different from large, impersonal national banks where you are just a number on a screen.

In a credit union, your local environment and your relationship with a loan officer actually carry weight. They offer products designed to help you save, borrow, and build a stronger future. If you prefer a mission-driven banking experience, a credit union is a refreshing change.

They often provide more personalized guidance during the application. This is incredibly helpful when you need to explain why your past bankruptcy is behind you and why your current situation is stable and looking up.

Pros:

  • Strong community roots and long-standing reputation.
  • Mission-driven approach to member well-being.
  • Diverse products for saving and borrowing.

Cons:

  • Geographic limitations may apply to membership.

6. VivaLoan
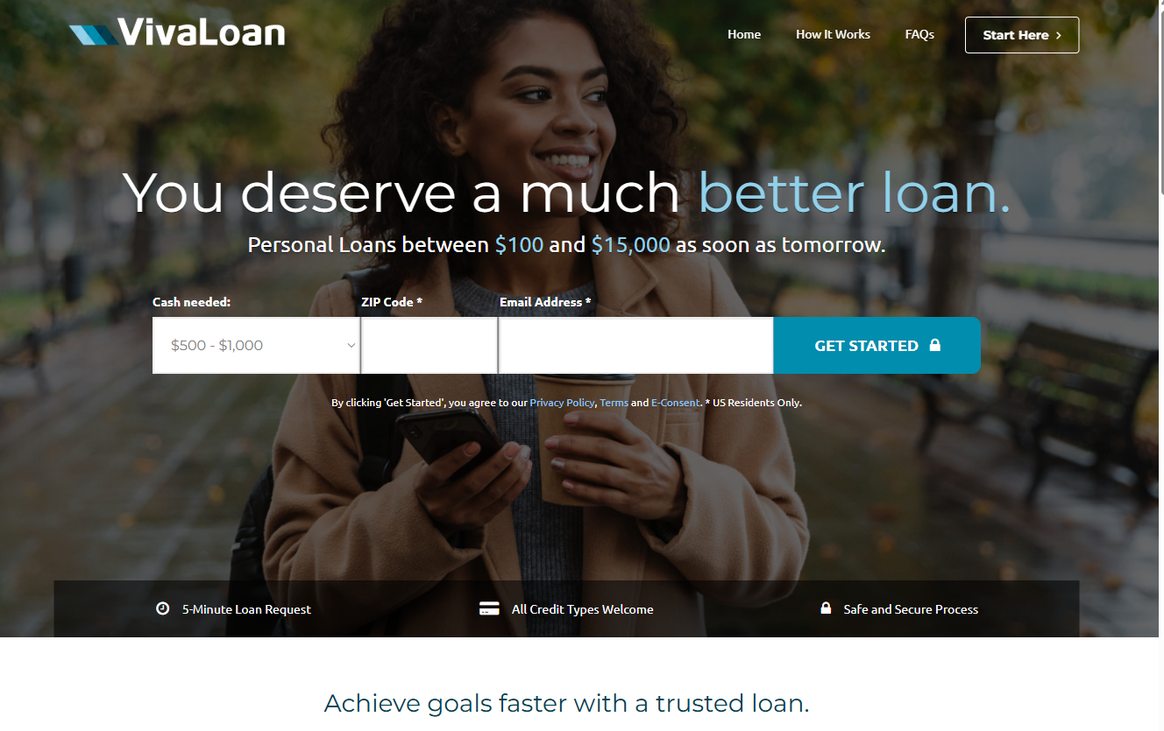
VivaLoan – vivaloan.com

VivaLoan is built for speed. They offer loans starting as low as $100 up to $15,000. This wide spectrum lets you find exactly what you need, whether it is a tiny amount for new tires or a larger sum for a major life event. This flexibility is vital if you are still in the stabilization phase of your recovery.

One of their best features is the speed of funding. You can often receive your money as soon as the next business day. With a five-minute application process and an open policy for all credit types, they are a lifeline in an emergency.

While the ease of use is hard to beat, you should use these funds strategically. You want to avoid falling into a cycle of high-interest borrowing that can keep you stuck.

Pros:

  • Extremely fast funding, often by the next business day.
  • Very low minimum loan amount of $100.
  • Welcomes all credit types.

Cons:

  • High speed and accessibility can come with higher costs.

7. World Finance
World Finance – worldfinance.com

World Finance is a specialized player in the market. They offer a variety of services, including retail and private banking. Their focus often leans toward more structured financial environments and specialized segments, providing options for people who do not fit into a standard consumer lending box.

This can include people with unconventional income streams or those needing very specific loan structures. They provide a deep look into both global and local economic trends for their clients.

For those seeking a more complex financial partner, they offer services that go beyond a simple personal loan. Their expertise is useful for borrowers navigating a sophisticated recovery involving multiple asset types.

Pros:

  • Wide breadth of financial services and insights.
  • Expertise in diverse banking sectors.
  • Professional focus on market trends.

Cons:

  • May be more complex than a standard consumer lender.

Strategies for Maximizing Your Approval Odds

Securing a loan after a bankruptcy discharge requires a strategic approach. Lenders want to see “stability indicators.” Even if your score is still recovering, you can improve your odds by providing organized documentation of your income. This means having recent pay stubs, bank statements, and tax returns ready to go. A lender is much more likely to say yes if they see a clear, unbroken line of income.

Another smart move is to consider a “secured” loan if “unsecured” options are proving too difficult. A secured loan is backed by an asset, like a car title or a savings account. Because the lender has collateral, their risk is much lower, which often leads to higher approval rates and better interest rates. Once you pay that loan back, your credit score usually gets a significant boost.

This path paves the way for the larger, unsecured loans you might need later on. It is a way to prove your reliability to the banks while you are still getting back on your feet.

Common Pitfalls to Avoid During Your Search

When you are looking for a loan, the biggest mistake is rushing into the first offer you see. You must compare the total cost of borrowing, not just the monthly payment. A low monthly payment can hide a much higher interest rate or a term that is so long you end up paying double what you borrowed. Always ask for the Annual Percentage Rate (APR) to see the true cost.

Another mistake is failing to check your credit report for errors before you apply. Even after a bankruptcy is discharged, mistakes can linger. A debt that was included in your bankruptcy might still show as “unpaid” on your report. Clean up your records first to give yourself the best chance of success.

Finally, read the fine print regarding prepayment penalties. Some lenders charge a fee if you try to pay the loan off early. This is the last thing you want when you are trying to move out of debt quickly. Approach your search with patience. The journey to financial health is a marathon, not a sprint.
The 6 Best Lenders for Holiday Loans for Bad Credit in 2026

Holiday loans for bad credit

The 6 Best Lenders for Holiday Loans for Bad Credit in 2026

Last updated: 2026-10-16

The holiday season often brings a whirlwind of expenses that can catch anyone off guard. Between unexpected gifts, last-minute travel tickets, and seasonal hosting costs like grocery surges and decor, the financial squeeze can feel overwhelming. For those facing the holidays with less-than-perfect credit, finding a reliable way to bridge the gap is essential for a stress-free December.

Rather than relying on high-interest payday loans that can lead to a cycle of debt, many are turning to specialized lenders that prioritize speed and accessibility. When selecting a lender, the priority shifts from finding the lowest APR to finding speed and accessibility.

A lender that offers quick funding can be a lifesaver when a last-minute purchase is needed, such as a sudden car repair required to get home for the holidays or an unexpected catering bill for a family gathering. It is vital to look for transparency regarding fees and how the application process might impact your current credit standing.

Understanding the difference between a “hard pull”—which can temporarily lower your score—and a “soft pull”—which is essentially harmless—is the first step in making an informed decision.

  1. JetzLoan
  2. Addition Fi
  3. OppLoans
  4. World Finance
  5. Sound Credit Union
  6. OneMain Financial

How These Holiday Lenders Were Evaluated

The ranking process focused on speed, accessibility, and the ability to secure funds despite a challenging credit history. Each option was assessed based on how quickly money hits a bank account and whether the application process involves a hard credit pull. This is a crucial distinction for anyone looking to shop around without damaging their score.

We analyzed the “time-to-cash” metric, which measures the elapsed time from the moment you click “apply” to the moment the funds are available for spending in your checking account. Accessibility was also a key pillar. Lenders were evaluated on their ability to serve individuals who might be turned down by traditional banks.

Traditional banking institutions often rely heavily on FICO scores and long-term credit history, which can be a barrier for those with recent setbacks. Our evaluation looked for providers that offer clear terms, minimal hidden fees, and a straightforward path from the initial application to receiving the necessary cash for seasonal needs.

We specifically prioritized lenders that provide a “pre-qualification” step, allowing you to see potential terms before committing to a formal application.

Lender Name Max Loan Amount Funding Speed Credit Impact Terms/Rates
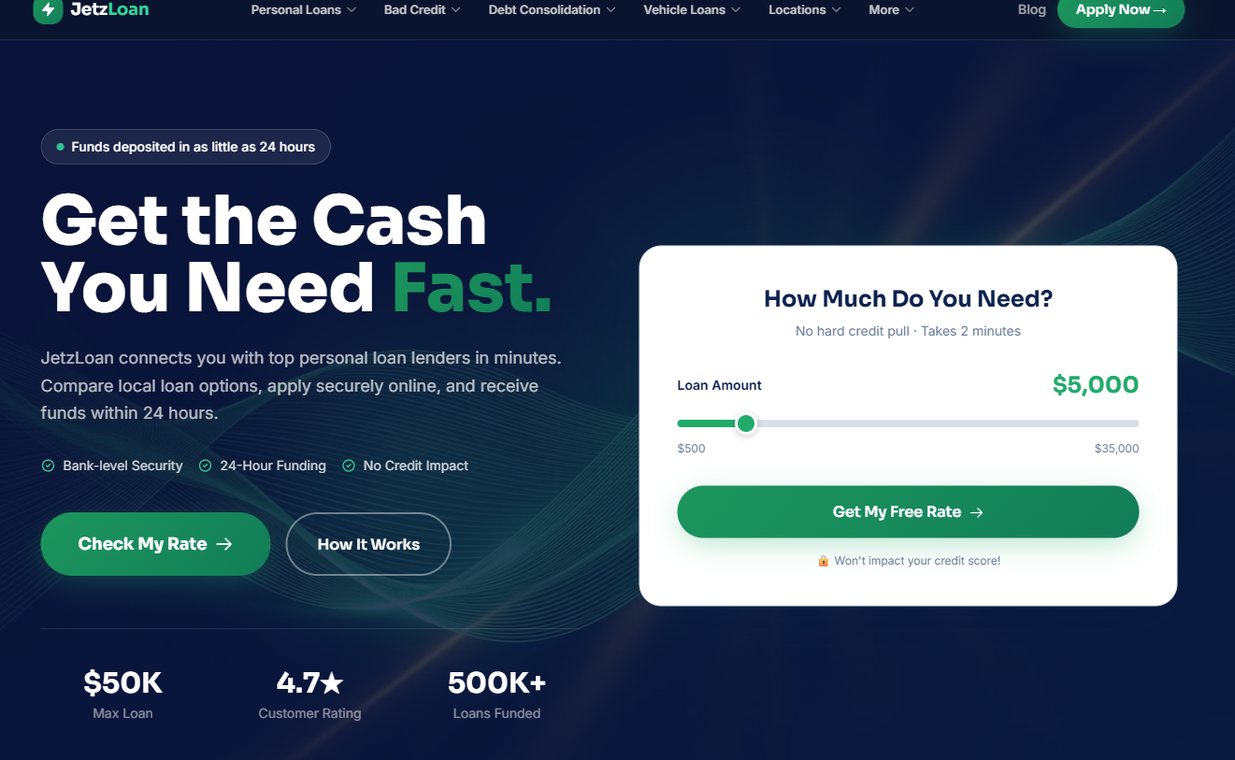
JetzLoan $50,000 As little as 24 hours No hard credit pull See site
Addition Fi See site See site See site See site
OppLoans See site Same-day funding available No FICO score impact See site
World Finance See site See site See site
Sound Credit Union See site See site See site
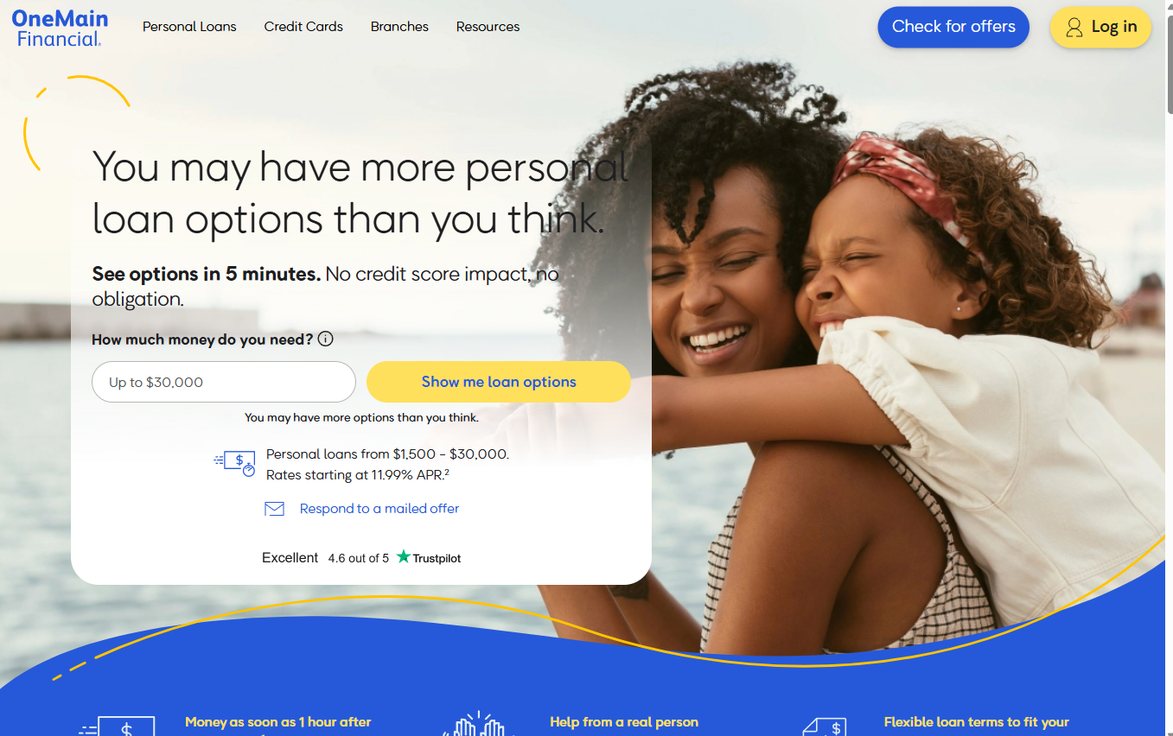
OneMain Financial $30,000 As soon as 1 hour No credit score impact Starting at 11.99% APR

Top Rated Lenders for Seasonal Funding

1. JetzLoan

JetzLoan – jetzloan.com

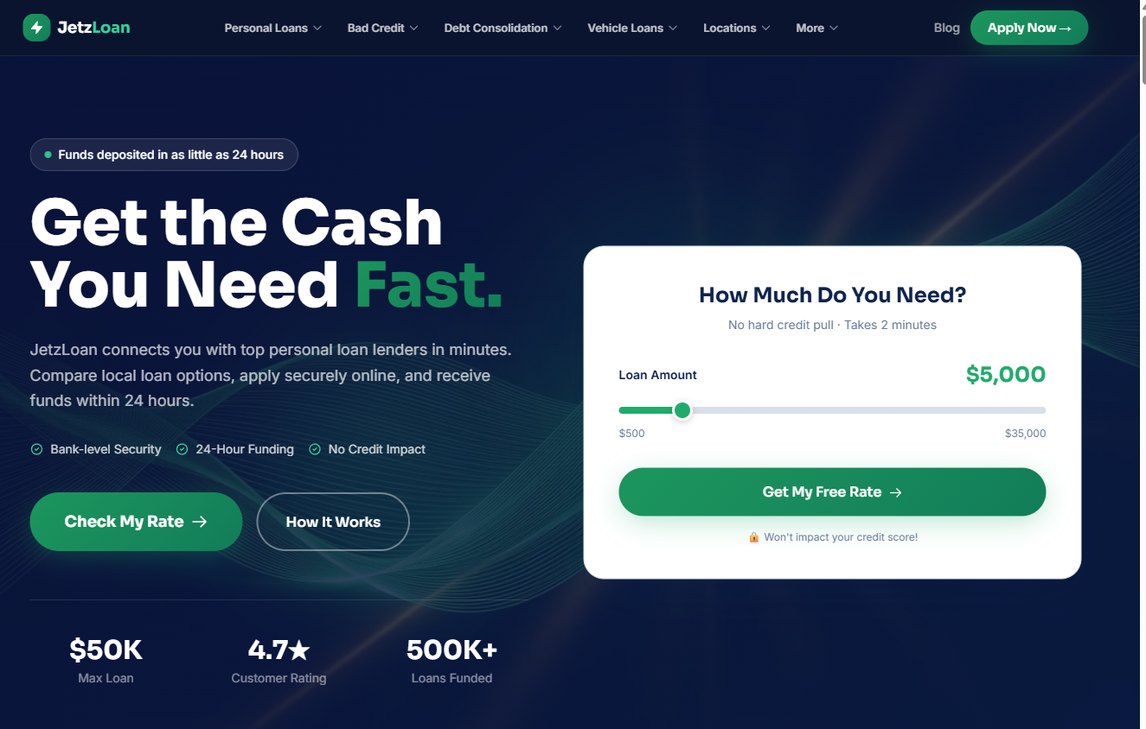
JetzLoan connects borrowers with top personal loan lenders in just a few minutes. It is an ideal solution for those who need a significant amount of cash, with loan limits reaching up to $50,000. The process is designed to be incredibly fast and transparent, removing the bureaucratic red tape often found in big-box banking. (jetzloan.com)

This option is perfect for individuals who need flexibility without the fear of a credit score dip. Because there is no hard credit pull during the initial check, you can explore your options freely. This “soft inquiry” approach allows you to gauge your eligibility and potential interest rates without the risk of a score decrease.

Funds can be deposited into your account in as little as 24 hours. This makes it suitable for those facing a tight deadline, such as a holiday travel booking that is about to expire.
Pros:

  • High maximum loan amount of $50,000
  • Fast 24-hour funding
  • No hard credit pull during the rate check

Cons:

  • Connecting with lenders takes a few minutes of application time

2. Addition Fi

Addition Fi – additionfi.com

Addition Financial operates as a full-service credit union, offering a wide variety of banking products. While they provide traditional loans, their focus is on building a long-term relationship with members. They offer competitive rates designed to help people borrow smarter and save more over time.

Unlike some predatory lenders, credit unions are member-owned. This means their primary goal is to serve their community rather than maximize shareholder profits. This is a great choice for those who want more than just a quick loan. They provide checking, savings, and various investment options.

It is a more stable, community-oriented approach for anyone looking to manage their finances more holistically during the holidays. If you are planning to make a large purchase, such as a used vehicle for holiday travel, their specialized loan products might offer better terms than a general personal loan.

Pros:

  • Diverse range of banking and investment services
  • Competitive rates on various products
  • Member referral incentives available

Cons:

  • May require membership to access full benefits

3. OppLoans

OppLoans – opploans.com

OppLoans is built around the idea that a credit score doesn’t tell the whole story. Their platform works with bank partners to provide personal loans that consider more than just a FICO number. They look at a broader range of financial data, which is helpful for individuals who may have a high income but a low credit score due to past student loans or medical debt.

Speed is their specialty, with same-day funding available if you are approved. The application is quick and easy, often providing decisions within minutes. This makes them a streamlined option for those facing an immediate cash crunch during the holiday season, such as a sudden need for emergency home repairs before guests arrive.

Pros:

  • Same-day funding available
  • Decisions often made in minutes
  • Does not affect FICO score when applying

Cons:

  • Approval is subject to bank partner criteria

4. World Finance

World Finance – worldfinance.com

World Finance provides a broad spectrum of financial services, ranging from retail banking to specialized asset management. They offer a sophisticated approach to finance that covers everything from insurance to complex investment strategies and corporate governance. Their infrastructure is designed to handle a wide variety of financial needs, making them a versatile option for a diverse client base.

This entity is suited for individuals or businesses needing specialized financial structures rather than a simple quick cash injection. Their scope is much wider than a standard personal lender, offering deep expertise in various global economic sectors.

If your holiday needs involve more complex financial planning or business-related seasonal inventory financing, their expertise may be relevant.
Pros:

  • Extensive range of financial services
  • Expertise in multiple banking sectors

Cons:

  • May be more complex than a simple holiday loan provider

5. Sound Credit Union

Sound Credit Union – soundcu.org

Sound Credit Union serves its members with a comprehensive suite of loan products. They offer everything from personal and student loans to specialized financing for RVs, boats, and motorcycles. Their focus is on providing a variety of paths to meet different financial goals, ensuring that members have options whether they are looking for a small personal loan or a large asset-backed loan.

For those who need a specific type of loan, such as an auto or home loan, they offer a structured environment. They provide a range of services including mobile and online banking, making it easy to manage your money on the go. This is particularly useful during the holidays when you might be traveling and need to check your balance or transfer funds instantly via your smartphone.

Pros:

  • Wide variety of specialized loan types
  • Convenient mobile and online banking
  • Comprehensive service list from checking to retirement

Cons:

  • May require specific membership criteria

6. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a powerhouse for those needing quick access to personal loans between $1,500 and $30,000. They pride themselves on offering more options than most people expect. You can often see your potential options in just five minutes without any obligation, which is ideal if you are comparing multiple lenders at once.

If you need money immediately, they offer a path to receive funds as soon as one hour after the loan is signed. With fixed monthly payments and terms ranging from 24 to 60 months, they provide a predictable way to handle seasonal expenses. This predictability is vital for budgeting; knowing exactly what you owe each month prevents any surprises when you are trying to save for January expenses.

Pros:

  • Extremely fast funding (as soon as 1 hour)
  • Fixed monthly payments for budget stability
  • Large network of 1,300 branches for personal help

Cons:

  • Interest rates can vary based on creditworthiness

Step-by-Step: How to Apply for Seasonal Funding

Securing a loan during the busy holiday season requires a methodical approach to ensure you get the best terms without unnecessary delays. Follow these steps to maximize your chances of success:

  1. Assess Your Total Need: Before applying, calculate exactly how much you need. Don’t just guess; look at your gift list, planned grocery budget, and any expected travel costs. Borrowing more than you need can lead to unnecessary interest costs.
  2. Check Your Credit Score: While many lenders offer soft pulls, knowing your score helps you set realistic expectations for the interest rates you might receive.
  3. Gather Documentation: To speed up the process, have your most recent pay stubs, proof of identity (like a driver’s license), and bank account details ready. Digital copies of these documents will significantly reduce application time.
  4. Compare Pre-Qualifications: Use the lenders mentioned above to check your eligibility. Focus on lenders that offer a “no hard credit pull” option to protect your score while you shop around.
  5. Review the Total Cost: Look beyond the monthly payment. Check the “Total Repayment Amount” to see exactly how much you will have paid by the end of the loan term.

Avoiding Common Financial Pitfalls

Before signing any agreement, it is vital to read the fine print. Many people fall into the trap of only looking at the monthly payment amount. However, the total cost of the loan is determined by the APR and the length of the term. A small monthly payment over a long period can end up costing significantly more in the long run.
For example, a $2,000 loan with a $100 monthly payment sounds manageable, but if the term is 36 months, you will have paid back $3,600—meaning you paid $1,600 in interest alone. Another mistake is failing to compare options. Even if you are in a rush, taking ten minutes to check a second or third lender can save hundreds of dollars.

Always ensure you are not paying hidden fees or unnecessary service charges that could eat into your holiday budget. Watch out for “origination fees”—charges taken directly from the loan amount before you even receive the cash—as these can significantly decrease the actual amount of money you receive.

Finally, consider your repayment plan. The goal of a holiday loan should be to bridge a temporary gap, not to create a long-term debt burden. Plan to pay the loan back as quickly as possible once the holiday season ends and your normal income stream resumes. By being diligent now, you can enjoy the festivities without the lingering shadow of financial stress in January.

Wo Glück auf Transparenz zusammenkommt: Luna Slots Casino für Deutschland

High Roller Casino Australia - #1 High Roller Casinos AU

Wir begrüßen Sie, einen Ort zu erkunden, an dem sich zwei scheinbare Gegensätze auf organische Weise verknüpfen: das spannende Flüstern des Glücks und die besänftigende Klarheit vollständiger Transparenz https://lunaslots-casino.com/. Für Spielerinnen und Spieler in Deutschland ist die Suche nach einem seriösen Online-Casino oft von Fragen bestimmt. Werden Gewinne verlässlich ausgezahlt? Sind die Spielmechanismen fair? Bei Luna Slots Casino erwidern wir diese Fragen nicht nur mit Worten, sondern mit einer konsequent gelebten Haltung. Wir sind überzeugt, dass authentisches Spielvergnügen nur dort entstehen kann, wo das Regelwerk glasklar ist und die Abläufe jederzeit nachvollziehbar wirken. Dieser Ansatz formt unsere tägliche Arbeit und macht aus flüchtigen Glücksmomenten eine vertrauensbasierte Beziehung, die auf Dauer konzipiert ist und kontinuierlich wächst.

Der Ansatz hinter Luna Slots Casino

Im Mittelpunkt unserer Überlegungen liegt ein einfaches Prinzip: Erfolg benötigt einen verlässlichen Rahmenbedingungen, um sich entfalten zu können. Wir haben Luna Slots Casino von Grund auf so entwickelt, dass die Lust am Spiel nie durch Unsicherheit beeinträchtigt wird. Für uns bedeutet das, jede individuelle Komponente der Plattform sorgfältig zu prüfen, von der Wahl der Spielgeräte bis zur Ausarbeitung der AGB. Wir möchten, dass Sie sich auf das Wichtige konzentrieren können – das Spielen der Walzen, die Spannung vor der nächsten Karte und den Zauber des Augenblicks, in dem sich ein Erfolg zeigt. Diese Philosophie ist kein Marketing-Gag, sondern der Wegweiser, der unser gesamtes Team lenkt und der in jeder Maßnahme fühlbar wird, die wir intern fällen und nach außen deutlich machen.

Wir sehen uns als Anbieter, die eine sorgsame Umgebung gestalten. In Deutschland, wo die Kontrolle des Glücksspiels zu berechtigterweise hohe Anforderungen setzt, präsentieren wir uns gezielt als Partner, der diese Bedingungen nicht als Bürde, sondern als Möglichkeit begreift. Wir haben die Erfahrung gesammelt, dass zufriedene Spieler die besten Repräsentanten sind. Deshalb investieren wir dauerhaft in die Verständlichkeit unserer Prozesse und in eine ehrliche Kommunikation. Bei Luna Slots Casino dreht es sich nicht um temporäre Effekte, sondern um eine langfristige Verbindung, die auf Respekt und gemeinsamem Verständnis aufbaut. Diese Grundeinstellung unterscheidet uns von Unternehmen, die Transparenz nur als Schlagwort nutzen, ohne sie mit Tiefe zu füllen.

Mobiles Spielen ohne Kompromisse

Die Mehrheit der Spieler in Deutschland benutzt heute mobile Geräte für den Zugriff zu Online-Casinos, und wir haben unsere Plattform passend optimiert. Luna Slots Casino funktioniert auf Smartphones und Tablets ohne die Notwendigkeit Download einer weiteren App, direkt über den mobilen Browser. Wir haben besonderen Wert darauf gelegt, dass die Benutzeroberfläche auf kleineren Bildschirmen nicht nur funktional, sondern auch ästhetisch ansprechend bleibt. Alle Spiele, die Sie vom Desktop wissen, stehen Ihnen auch unterwegs in ganzer Qualität zur Verfügung. Die Ladezeiten haben wir durch effiziente Programmierung auf ein Minimum reduziert, damit der Spielfluss nicht unterbrochen wird.

Die mobile Version unserer Plattform garantiert den identischen Funktionsumfang wie die Desktop-Ansicht. Sie können Ein- und Auszahlungen vornehmen, den Kundenservice erreichen und auf Ihre komplette Spielhistorie einsehen. Wir haben die Navigation speziell für die Touch-Bedienung optimiert, sodass Buttons und Menüs auch auf kleineren Displays zielgenau zu treffen sind. Für uns bedeutet mobiles Spielen nicht, Abstriche bei der Sicherheit oder der Transparenz machen zu müssen. Die Verschlüsselungstechnologie und die fairen Spieloptionen sind auf jedem Gerät identisch. So bleibt das Versprechen von Luna Slots Casino auch unterwegs in vollem Umfang gültig.

Glücksgefühl im digitalen Zeitalter: Wie Zufall und Fairness zusammenwirken

Der Begriff Glück wird oft schwärmerisch verklärt, dabei folgt er in einem vertrauenswürdigen Online-Casino harten mathematischen Gesetzen. Wir bei Luna Slots Casino setzen auf geprüfte Zufallszahlengeneratoren, die gewährleisten, dass jede Spielrunde unabhängig von der vorherigen ist. Für Sie als Spieler bedeutet das: Weder eine mutmaßliche Glückssträhne noch eine Pechserie haben den geringsten Einfluss auf den nächsten Spin. Diese Eigenständigkeit ist die maschinelle Grundlage für gerechtes Spiel. Wir verdeutlichen diesen Sachverhalt bewusst immer wieder, weil wir das Vertrauen in die Technik ausbauen möchten. Nur wer versteht, dass der Zufall kein Gedächtnis hat, kann das Auf und Ab des Spiels ruhig annehmen.

Für das Publikum in Deutschland, das traditionell ein ausgeprägtes Bewusstsein für technische Standards aufweist, ist diese fachliche Fundierung ein wichtiges Argument. Wir verbinden das sachliche Prinzip des Zufalls mit der gefühlsmäßigen Anziehungskraft detailreich gestalteter Spielautomaten. Die Grafiken, Soundeffekte und Animationen sind das Gewand, in das sich die Mathematik hüllt. Doch unter der Oberfläche agiert ein präziser Algorithmus, der keine Bevorzugung kennt. Diese Kombination aus rationaler Berechnung und sinnlichem Erleben macht für uns den spezifischen Reiz aus. Bei Luna Slots Casino können Sie sich darauf vertrauen, dass das Glück tatsächlich jedem identisch gewogen ist – unabhängig von Spieleinsatz oder Spielhäufigkeit.

Slotauswahl für unterschiedliche Geschmack

Die Auswahl an Spielautomaten bei Luna Slots Casino ist das Ergebnis einer sorgfältigen Kuratierung. Wir fügen nicht jedes Spiel in unser Portfolio ein, sondern überprüfen jeden Titel auf seine systemische Zuverlässigkeit, seine Auszahlungsquote und seinen Freizeitwert. Unser Portfolio umfasst herkömmliche Walzenspiele mit niedrigen Gewinnlinien gleichermaßen wie aktuelle Video-Slots mit ausgefeilten Bonusrunden und wachsenden Jackpots. Wir arbeiten mit renommierten Entwicklerstudios im Team, die für ihre fairen Spielmechaniken und ihre kreativen Themenwelten geschätzt sind. Diese Allianzen ermöglichen es uns, kontinuierlich neue Titel zu präsentieren, ohne die Qualität aus den Augen zu verlieren.

Für Gamer in Deutschland haben wir ein erhöhtes Augenmerk auf Spiele, die inhaltlich oder verbal auf den deutschen Raum zugeschnitten sind. Wir wissen, dass gewohnte Symbole und eine angepasste Benutzeroberfläche das Spielerfahrung intensivieren. Zugleich bieten wir weltweite Top-Titel, die weltweit für Faszination sorgen. Die Bedienung durch unser Portfolio entwerfen wir so einfach wie möglich. Suchfilter nach Genres, Funktionen oder Risikostufe unterstützen Ihnen, zügig den passenden Slot zu entdecken. Wir möchten, dass die Suche nach dem nächsten Lieblingsspiel gleichsam viel Spaß beschert wie das Gamen selbst.

Sicherheit und Datenvertraulichkeit nach deutschen Vorgaben

Der Schutz Ihrer eigenen Daten genießt bei uns oberste Priorität. Wir haben unsere Schutzarchitektur an den hohen Anforderungen angepasst, die in Deutschland und der Europäischen Union bestehen. Das bedeutet praktisch: Jegliche Datenübertragungen zwischen Ihrem Gerät und unseren Servern werden mit modernster SSL-Verschlüsselung geschützt. Wir setzen außerdem auf mehrschichtige Authentifizierungsverfahren, um unerlaubte Zugriffe auf Spielerkonten wirksam zu verhindern. Diese technologischen Maßnahmen werden turnusmäßig von unabhängigen Sicherheitsexperten überprüft und angepasst. Wir sehen Datenschutz nicht als störende Pflicht, sondern als grundlegenden Bestandteil unseres Qualitätsversprechens.

Außerdem verpflichten wir uns zur Einhaltung der Datenschutz-Grundverordnung, die in Deutschland einen besonders hohen Stellenwert besitzt. Wir erfassen nur die Daten, die für die Abwicklung des Spielbetriebs und die Einhaltung regulatorischer Pflichten notwendig sind. Eine Weitergabe an Dritte zu Werbezwecken erfolgt nicht. In unserem Datenschutz-Center erläutern wir in einfacher Sprache, welche Informationen wir speichern und welche Rechte Sie als Nutzer besitzen. Wir laden ein alle unsere Mitglieder, sich diese Informationen in Ruhe durchzulesen. Bei Luna Slots Casino wollen Sie sich voll und ganz auf das Spiel fokussieren können, ohne sich Sorgen über die Sicherheit Ihrer Daten machen zu müssen.

Transaktionen: Klarheit bei jeder Transaktion

Finanzielle Transaktionen sind der heikelste Bereich eines jeglichen Online-Casinos, und wir gehen mit sie mit der nötigen Sorgfalt. Bei Luna Slots Casino erhalten Sie eine übersichtliche Darstellung aller verfügbaren Zahlungsmethoden, die für den deutschen Markt von Bedeutung sind. Wir stellen für jede Option die typischen Bearbeitungszeiten und eventuelle Limits bekannt, bevor Sie sich für einen Weg entscheiden. Unser Ziel ist es, dass Sie schon vor der ersten Einzahlung genau kennen, was Sie erwartet. Diese Vorab-Information bietet die Sicherheit, die für ein angenehmes Spielerlebnis unerlässlich ist. Wir aktualisieren unsere Angaben regelmäßig, um stets den aktuellen Stand darzustellen.

Unser Zahlungssystem besticht durch folgende Eigenschaften:

  • Rasche Verifizierung neuer Konten, um Auszahlungen ohne überflüssige Verzögerungen zu sicherzustellen.
  • Mehrere bekannte Zahlungsdienstleister, die in Deutschland weit gängig und als sicher anerkannt sind.
  • Offene Kommunikation von eventuellen Prüfzeiträumen, die sich aus rechtlichen Vorgaben ergeben.
  • Keinerlei versteckten Gebühren auf unserer Seite; entstehende Kosten werden klar dargestellt.

Wir sind uns bewusst, dass vor allem bei Auszahlungen das Vertrauen in ein Casino auf die Probe gestellt wird. Deshalb haben wir unsere internen Prozesse so optimiert, dass legitime Auszahlungsanfragen rasch bearbeitet werden. Sollte es im Einzelfall zu Rückfragen gelangen, etwa im Rahmen der notwendigen Identitätsprüfung, teilen mit wir den Status offen über Ihr Konto-Dashboard. Wir bitten um Verständnis, dass diese Prüfungen dem Schutz aller Beteiligten zugutekommen und eine gesetzliche Anforderung darstellen, die wir nicht vermeiden können und wollen. Bei Luna Slots Casino ist jeder Schritt einsehbar dokumentiert.

Kundenservice, der den Bezeichnung erhält

Ein exzellenter Kundenservice ist für uns der konkrete Ausdruck unserer Hochachtung gegenüber den Spielern. Wir haben ein Team aus qualifizierten Mitarbeitern aufgebaut, das sich durch Kompetenz und Feingefühl hervortut. Sie erreichen uns über mehrere Kanäle, wie einen Live-Chat, der während der ausgedehnten Servicezeiten aktiv ist. Wir schätzen es, Anfragen nicht mit standardisierten Textbausteinen zu erwidern, sondern maßgeschneidert auf Ihr Anliegen einzugehen. Vor allem bei anspruchsvolleren Fragen zu Bonusbedingungen oder technologiebezogenen Abläufen ist uns eine persönliche und exakte Antwort bedeutsam.

Für unsere Nutzer in Deutschland bieten wir die Kommunikation natürlich in deutscher Sprache bereit. Wir erkennen, dass verbale Barrieren in sensiblen Situationen zügig zu Missverständnissen kommen können. Daher stellen wir sicher, dass unsere Support-Mitarbeiter die Nuancen der deutschen Sprache kennen und kulturell bedingte Besonderheiten verstehen. Unser Anspruch ist es, jede Anfrage beim ersten Kontakt endgültig zu lösen. Falls dies ausnahmsweise nicht umsetzbar sein, geben wir Ihnen Bescheid über den Bearbeitungsstand. Wir betrachten den Kundenservice nicht als Kostenfaktor, sondern als Gelegenheit, die Beziehung zu unseren Kunden zu intensivieren und Vertrauensbasis aufzubauen.

Verantwortungsvolles Spielen als praktizierte Haltung

Wir betrachten den bewussten Umgang mit Glücksspielen als wesentlichen Teil unseres Angebots, nicht als störende Aufgabe. Bei Luna Slots Casino finden Sie eine Reihe von Werkzeugen, mit denen Sie Ihr Spielverhalten selbst steuern können. Dazu gehören eigene Einzahlungslimits, die Sie anpassbar an Ihre persönlichen Verhältnisse anpassen können, sowie die Option, sich für bestimmte Zeiträume selbst zu sperren. Wir informieren proaktiv über diese Funktionen und motivieren unsere Spieler, sie als selbstverständliche Begleiter des Spielens zu nutzen. Prävention startet für uns mit Aufklärung, nicht mit Verboten.

Für den deutschen Markt, in dem das Thema Spielerschutz einen außergewöhnlich wichtigen Stellenwert einnimmt, gehen wir über die rechtlichen Mindestanforderungen hinaus. Wir stellen Informationsmaterialien zur Verfügung, die Anzeichen problematischen Spielverhaltens eindeutig beschreiben. Zudem kooperieren wir mit externen Beratungsstellen, an die wir bei Bedarf empfehlen. Unser System erkennt ungewöhnliche Aktivitätsmuster und kann automatisch Hinweise einblenden, ohne gängelnd zu wirken. Wir sind davon überzeugt, dass ein Casino nur dann erfolgreich kann, wenn seine Spieler wohlauf bleiben. Diese Haltung beeinflusst jede Maßnahme, die wir im Bereich des Spielerschutzes anwenden.

Top 4 Dental Financing Options Ranked for 2026

Dental financing

Top 4 Dental Financing Options Ranked for 2026

Last updated: 2026-10-16

Walking into a dentist’s office only to receive a price tag that feels like a punch to the gut is a common nightmare. Most people find themselves staring at a bill for implants or crowns, wondering if they will ever see their bank account balance rise again. Whether it is an emergency root canal necessitated by a sudden infection or a planned cosmetic procedure like veneers that promises a total transformation, the upfront cost can be staggering. Finding a way to bridge that gap without breaking the bank is essential for maintaining both your physical health and your financial stability.

Choosing the right way to pay for your smile isn’t just about the monthly payment. It involves looking at interest rates, how a lender treats your credit score, and how quickly you can get the green light. A high interest rate might make the monthly installment seem manageable, but over a 24-month period, you could end up paying thousands more than the actual cost of the dental work. Conversely, a lender that requires an impeccable credit score might leave you in pain while you wait weeks for an approval. This ranking looks at the most prominent players in the market to help you decide which path leads to a healthy smile.

  1. CareCredit
  2. Cherry
  3. FastLendGo
  4. iCare

How These Dental Payment Solutions Were Evaluated

The selection process focused on the specific needs of patients facing unexpected oral health costs. We looked at whether a lender provides quick decisions, which is vital when a toothache won’t quit. Speed often matters just as much as the actual cost of the loan when you are in pain. If you are sitting in a waiting room with a throbbing molar, you don’t want to be told you have to wait three business days for a manual underwriting process to finish. You need a solution that works in real-time.

We also weighed the accessibility of these options for individuals with varying credit profiles. Some patients have pristine scores and can qualify for the lowest possible APRs, while others are just trying to keep their heads above water and may have a history of late payments or high credit utilization. A good financing partner should offer a way forward, regardless of whether your credit history is a polished gem or a bit of a mess. We evaluated lenders based on three primary pillars: speed of approval, ease of application, and the breadth of credit eligibility. We also considered the “hidden” costs, such as origination fees or penalties for early repayment, which can turn a simple payment plan into a long-term debt trap.

Lender Name Primary Use Case Speed of Decision Credit Requirement Loan Amounts
CareCredit Health & Wellness Instant Subject to Approval See site
Cherry Flexible Payment Plans Fast Broad Eligibility See site
FastLendGo Personal Loans Quick All Credit Tiers $500 – $5,000+
iCare No-Nonsense Financing Instant No Credit Check See site

Understanding the Cost of Delaying Care

It is tempting to push a dental bill to the “next month” pile, but in dentistry, procrastination is often the most expensive financial decision you can make. Oral health issues are rarely static; they are progressive. A small cavity that costs $200 to fix today can evolve into a cracked tooth requiring a $1,500 crown in six months, or an even more expensive $2,500 root canal and buildup if the infection reaches the nerve.

When comparing financing options, it is helpful to view the cost of the loan against the cost of the untreated condition. If a lender offers a 0% interest plan for six months, the “cost” of the money is effectively zero, making it a highly efficient way to manage cash flow. However, if you choose a high-interest personal loan to avoid a waiting period, you must calculate if the interest paid is less than the projected increase in the cost of the dental procedure if it worsens. In many cases, the interest on a loan is a small price to pay to prevent a surgical emergency later.

Ranking the Best Lenders for Your Dental Care

1. CareCredit

CareCredit – carecredit.com

CareCredit operates as a specialized health and wellness credit card designed for medical and dental needs. It is a heavy hitter in the industry, accepted at over 285,000 locations. This makes it a very convenient choice if your dentist is already part of their vast network of providers. Because it is a dedicated credit line, it doesn’t clutter your primary personal credit card utilization, which can help keep your credit score stable if managed correctly.

The application process is designed to be painless, offering instant credit decisions so you aren’t left waiting. It is an ideal solution for those who want a dedicated line of credit specifically for health-related expenses and want to pay over time. Many providers offer “deferred interest” promotions—for example, 6, 12, or 24 months of 0% interest. This is a powerful tool, but it comes with a significant caveat: if you fail to pay the full balance by the end of the promotional period, you are often backdated and charged all the interest that would have accrued from day one. You must be disciplined to make this work.

Pros:

  • Extremely wide acceptance at dental offices nationwide.
  • Instant decisions mean you can start treatment quickly.
  • Prequalification does not impact your credit score.

Cons:

  • Subject to credit approval and standard card terms.

2. Cherry

Cherry – trycherry.com

Cherry has carved out a niche by offering more modern, patient-friendly payment plans. They are known for having broader eligibility criteria, which is a breath of fresh air for those who might be nervous about traditional bank loans. It feels less like a rigid contract and more like a helpful tool. Instead of a revolving credit card, Cherry often functions more like a structured installment loan, where you know exactly how much you owe and when each payment is due.

This option is perfect for patients who want a straightforward payment structure without the heavy lifting of traditional credit cards. It aims to make ownership of your dental care feel immediate and much less intimidating for the average person. Because Cherry integrates directly with many dental practice management softwares, the checkout process at the dentist’s office is often as simple as a few clicks on a tablet, allowing you to walk out with your treatment scheduled and your financing settled in minutes.

Pros:

  • Broad eligibility criteria for a wider range of people.
  • Provides a flexible alternative to standard credit cards.
  • Streamlined process for quick payment plan setups.

Cons:

  • May not offer the same high limits as traditional credit lines.

3. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a versatile partner for various personal financing needs, including dental work. They cater to a wide spectrum of borrowers, from those with great credit to those struggling with bad credit. This makes them a go-to for people who need a personal loan specifically for dental care where the dentist’s in-house financing might be too restrictive or unavailable. Unlike a credit card, which you use at the point of sale, a personal loan from FastLendGo is often deposited directly into your bank account.

If you need a lump sum of cash to cover a large procedure, this is a strong contender. They offer various loan sizes, starting from small amounts like $500 up to $5,000 or more, making them quite flexible for different treatment scales. This is particularly useful if you are paying a dentist who does not participate in any third-party financing programs. Having the cash in hand allows you to negotiate a “cash discount” with some providers, which can sometimes offset the interest cost of the loan itself.

Pros:

  • Accepts various credit levels, including bad credit.
  • Offers specific loan amounts for different needs.
  • Quick access to cash for immediate dental repairs.

Cons:

  • The interest rates can vary significantly based on credit.

4. iCare

iCare – icarefinance.com

iCare takes a very different approach with its patented, no-nonsense program. The standout feature here is the ability to offer 0% interest financing with no credit check and instant approval. This is a game-changer for patients who cannot afford to wait or undergo a rigorous credit investigation. For many, the idea of a “credit check” is a source of immense anxiety, fearing that a rejection will further damage their score or that a high-interest rate will follow them for years.

This option is tailor-made for the patient who needs a customized, hassle-free way to pay for care. It removes the “fear factor” often associated with financing, allowing the focus to remain on oral health rather than financial anxiety. It is an ideal bridge for those who might be in a temporary cash crunch but have a steady income that supports monthly installments. By decoupling the financing from traditional credit scoring, iCare opens doors for many who would otherwise be forced to delay essential care.

Pros:

  • Offers 0% interest options.
  • No credit check required for instant approval.
  • Highly customizable financing structures.

Cons:

  • Availability may depend on the specific provider’s setup.

Comparing Financing Types: Credit Cards vs. Personal Loans vs. Installment Plans

To choose the best path, you must understand the structural differences between these financial tools. Not all “debt” is created equal, and the way you repay it determines your long-term financial health.

Feature Credit Card (e.g., CareCredit) Personal Loan (e.g., FastLendGo) Installment Plan (e.g., Cherry)
Structure Revolving (can be used repeatedly) Lump Sum (one-time use) Fixed Term (fixed monthly payments)
Interest Type Often promotional 0% (then high APR) Fixed APR throughout term Typically fixed or low-cost
Impact on Credit Affects utilization and payment history Affects debt-to-income ratio Minimal impact if structured as a service
Best For Long-term, high-value procedures When you need cash in your own bank account Predictable, monthly budgeting

Avoiding Common Financial Pitfalls

Before you sign on the dotted line, always look at the fine print regarding interest. It is easy to get caught up in the excitement of a “no credit check” offer, but you must understand if the total cost of the procedure increases significantly due to fees or deferred interest. For instance, if a plan offers 0% interest for 12 months but charges a 5% “origination fee” upfront, your actual cost of borrowing is higher than it appears. Always ask your dentist how they handle these specific providers and if there are any administrative fees associated with setting up the plan.

Another mistake is ignoring the impact on your budget. A monthly payment might look small on paper—say, $75 a month—but when stacked with a car payment, a phone bill, and rising grocery costs, it can become a mountain that is difficult to climb. A “payment shock” occurs when a patient realizes they have committed to several different financing plans at once. Make sure the payment schedule fits your lifestyle, not just your immediate need for a new tooth. Always aim to pay off your dental financing as quickly as possible; even if you have a 0% interest plan, paying it off early provides peace of mind and frees up your monthly cash flow for other life necessities.

Top 6 Lenders for Bad Credit Loans in Texas: 2026 Rankings

Bad credit loans texas

Top 6 Lenders for Bad Credit Loans in Texas: 2026 Rankings

Last updated: 2026-10-16

Trying to bridge a financial gap when your credit score is struggling feels like running through waist-deep mud. In Texas, many people face sudden car repairs or medical bills without the safety net of a high credit score. It is a stressful spot that demands quick thinking and even faster action to fix.

Whether you are dealing with a broken HVAC system during a Houston summer or an unexpected transmission failure on a long haul through West Texas, the need for cash is often immediate. You cannot wait weeks for a bank to approve a request when your car needs to get back on the road today.

This list highlights specific lenders that serve the Lone Star State. When looking at these options, the main concerns are how fast you get the money, whether you can apply without a hard credit pull, and if the lender understands the needs of Texans. Each entry serves a different purpose, from small cash advances to large home improvement funds.

Understanding the difference between a micro-advance app and a structured personal loan is the first step toward making a decision that strengthens your financial position. You want an option that solves your immediate problem rather than one that creates a new one later on.

  1. TexasLoansToday
  2. Jora Credit
  3. Dave
  4. Swoop US
  5. CareCredit
  6. USDA Rural Development

How Texas Lenders Were Evaluated

The selection process focused on accessibility and speed for residents living in Texas cities and rural areas. A major priority was finding lenders that offer quick approval processes and do not immediately damage a consumer’s credit score during the initial inquiry. Protecting a fragile financial standing is vital when you are already in a tight spot.

We specifically looked for providers that utilize soft credit pulls for the pre-qualification stage. This allows Texans to “window shop” for the best rates without the penalty of a hard inquiry on their credit report. You should be able to see your options before you commit to anything that affects your score.

We also looked at the diversity of loan products available. Some lenders specialize in tiny, instant cash boosts for groceries, while others provide larger sums for significant life changes. We compared the speed of disbursement, the ease of the digital interface, and the geographical reach of each provider.

This ensures that whether a person needs $500 for an emergency utility bill or $35,000 for a debt consolidation project, there is a relevant option within this specific ranking. Every financial emergency is different, so your options should be too.

Lender Name Loan Amounts Funding Speed Credit Impact Best For
TexasLoansToday $500 – $35,000 Within 24 hours No hard credit pull Statewide personal loans
Jora Credit See site Minutes See site Online/Check options
Dave Up to $500 5 minutes or less No credit check Small cash advances
Swoop US See site See site See site Business funding
CareCredit See site Instant decisions No impact to prequalify Health and wellness
USDA Rural Development See site See site See site Rural home loans

Top Ranked Lenders for Texas Residents

1. TexasLoansToday

TexasLoansToday – texasloanstoday.com

TexasLoansToday connects Texans with a variety of top lenders across the state. It is designed for those who want to compare different options without the fear of a hard credit pull. This is a massive relief for anyone currently struggling to keep their score from dipping further. Instead of applying to five different banks and seeing five different inquiries on your report, you can use this service to see what matches your profile first. (texasloanstoday.com)

The service covers over 1,200 Texas cities and towns, making it highly accessible for both urban and rural dwellers. Whether you are in the heart of Dallas or a small community in the Panhandle, the digital infrastructure is built to reach you. With rates starting as low as 3.5% and the potential to receive funds within 24 hours, it moves much faster than traditional bank loans, which can often take several business days to process and verify.

Pros:

  • Covers over 1,200 Texas cities and towns
  • No hard credit pull during the application
  • Funds can arrive within 24 hours
  • Loan amounts up to $35,000

Cons:

  • Requires a 2-minute application to start the process

2. Jora Credit

Jora Credit – joracredit.com

Jora Credit is a direct lender that focuses on making the online loan process as painless as possible. They offer a unique flexibility by providing funds either through direct online transfers or via a physical check. This caters to people who might prefer traditional banking methods or those who may be experiencing temporary issues with their primary checking account and need a more reliable delivery method like a mailed check.

They provide solutions for various emergencies, including home repairs, auto services, or other urgent needs. The application process is streamlined to provide a decision within minutes. This is essential when a car is stuck in the shop or a roof is leaking and the damage is increasing by the hour. Their system is designed to handle the urgency of modern life, reducing the back-and-forth communication often required by legacy lending institutions.

Pros:

  • Direct lender with quick decisions
  • Options for online or check-based funding
  • Simple online application process

Cons:

  • Decision speed depends on application completeness

3. Dave

Dave – dave.com

Dave is not your typical heavy-duty lender; it is more of a digital lifeline for those living paycheck to paycheck. Their ExtraCash feature allows users to grab up to $500 almost instantly to cover immediate expenses like gas or groceries. It is a perfect tool for managing small, temporary cash flow gaps that occur between pay periods. Instead of turning to a high-interest payday loan, Dave offers a more modern, technology-driven alternative.

The technology behind the app, CashAI, looks at over 180 data points to determine eligibility, which means you aren’t strictly judged by a traditional credit score. It examines your banking history, income consistency, and spending habits to assess risk. This is a modern approach for the modern gig worker, freelancer, or anyone with irregular income who might not fit into the narrow boxes used by traditional credit bureaus.

Pros:

  • Extremely fast funding, often in 5 minutes
  • No interest or late fees on ExtraCash
  • No credit check required

Cons:

  • Low maximum limit of $500

4. Swoop US

Swoop US – swoopfunding.com

Swoop US shifts the focus away from individual personal needs and toward the backbone of the economy: small businesses. This platform is designed to streamline access to various types of funding, helping entrepreneurs get off the ground or fuel their next stage of growth. For a small business owner in Austin or San Antonio, waiting weeks for a bank loan can mean missing out on a critical inventory purchase or a seasonal marketing opportunity.

They offer a wide spectrum of financial products, including grants, working capital loans, and even asset finance. It is a sophisticated platform that looks at annual revenue and business age to match owners with the right kind of capital. By analyzing business health through multiple data streams, they can often provide solutions that traditional banks, with their rigid requirements, might overlook.

Pros:

  • Broad range of business funding types
  • Includes grants and tax credits
  • Streamlined access to growth capital

Cons:

  • Primarily focused on business rather than personal use

5. CareCredit

CareCredit – carecredit.com

CareCredit is a specialized option that targets the intersection of finance and health. It operates as a health and wellness credit card, allowing users to pay for medical or dental procedures over time. It is a vital resource for those facing high-cost healthcare needs, such as emergency dental work, vision correction, or veterinary expenses, which can often feel impossible to pay for in one lump sum.

The application process is quick, and they offer instant credit decisions. This can be a lifesaver when an unexpected medical procedure arises and the patient needs to know immediately if they can afford the care. Many providers offer promotional financing periods, such as 6 or 12 months of no interest, making it a powerful tool if you can pay the balance off within that specific window.

Pros:

  • Accepted at over 285,000 locations
  • Instant credit decisions
  • Flexible financing for healthcare

Cons:

  • Subject to credit approval

6. USDA Rural Development

USDA Rural Development – rd.usda.gov

For those living outside the bustling Texas metropolitan areas, USDA Rural Development offers a lifeline that most commercial lenders ignore. They provide specialized loans and grants specifically designed to help people in rural communities build, buy, or repair homes. This is particularly relevant in the vast stretches of West Texas and the Hill Country where traditional banking branches may be sparse.

This is a government-backed resource aimed at strengthening rural economies and expanding opportunities for long-term residency. While it may not be the fastest way to get cash for a weekend trip or a small repair, it is an incredibly powerful tool for long-term stability and homeownership. Programs like the Single Family Housing Direct Homeownership Loans can provide much-needed assistance to those who meet the income and location requirements.

Pros:

  • Specifically for rural communities
  • Supports home buying, building, and repair
  • Includes both loans and grants

Cons:

  • Highly specific eligibility requirements for rural areas

Understanding the True Cost of Borrowing

Before signing any loan agreement, you must understand the mathematical reality of the debt you are taking on. A common mistake is focusing solely on the monthly payment. While a low monthly payment makes a loan feel manageable, it often indicates a much longer repayment term, which leads to paying significantly more in total interest. For example, a $2,000 loan with a $50 monthly payment sounds affordable, but if that term lasts 60 months, you could end up paying nearly double the original amount.

To avoid this, perform a “Total Cost Calculation” before you commit. Take the monthly payment amount, multiply it by the number of months in the loan term, and then subtract the original principal. The result is the actual cost of the interest. If that number feels too high for the benefit you are receiving, you should keep looking or consider a different financial strategy, such as debt consolidation or negotiating a payment plan with your original creditor.

Preparing for a Successful Loan Application

Even when working with lenders who specialize in bad credit, being prepared can significantly increase your chances of approval and help you secure a better interest rate. Preparation starts with organization. Before you sit down to fill out an application for a service like TexasLoansToday or Jora Credit, have your essential documents ready to prevent delays. Most lenders will require:

  • Proof of Identity: A valid Texas Driver’s License or State ID.
  • Proof of Income: Recent pay stubs, W-2 forms, or bank statements if you are self-employed or a gig worker.
  • Proof of Residence: A recent utility bill (water, electric, or gas) that clearly shows your name and Texas address.
  • Banking Information: Your routing and account numbers for direct deposit.

Beyond documentation, a “financial hygiene” check is recommended. Even if you are applying for a no-credit-check advance via an app like Dave, having your bank statements clean of excessive overdraft fees can improve your internal score with the lender’s proprietary algorithms. If you are applying for a larger personal loan, ensuring your current debt-to-income ratio is as low as possible by paying down small balances before applying can work in your favor.

Avoiding Common Financial Pitfalls

When navigating the world of bad credit loans, it is easy to get swept up in the excitement of a quick approval. However, it is vital to read the fine print regarding interest rates and repayment terms. What looks like a small amount of money today can become a massive burden if the terms are not understood. Many lenders use “effective” rates that are much higher than the “nominal” rates stated in the marketing materials.

One major mistake is ignoring the total cost of borrowing. Always ask how much you will have paid back by the end of the loan term. Additionally, using high-interest loans to pay off other debts can sometimes be a temporary fix that leads to a long-term spiral if not managed with a strict budget. If you use a high-interest personal loan to pay off a credit card, but then continue to use that credit card, you have effectively doubled your debt instead of consolidating it.

It is also wise to check for any hidden fees that might be tucked away in the contract. Some lenders might offer fast cash but charge significant administrative or processing fees. Some may also include “prepayment penalties,” which charge you a fee if you try to pay the loan off early to save on interest. Taking a few extra minutes to verify the total cost of credit can save a lot of heartache in the months to come and ensure that your quick financial fix doesn’t become a long-term obstacle.

Top 5 Lenders for Car Repair Loans for Bad Credit in 2026

Car repair loans for bad credit

Top 5 Lenders for Car Repair Loans for Bad Credit in 2026

Last updated: 2026-10-16

Walking into a mechanic’s shop only to find out your transmission needs a complete overhaul is a gut punch. When the repair bill looks more like a mortgage payment, the stress can feel overwhelming. For many drivers, a sudden mechanical failure is a crisis that demands immediate cash to keep life moving.

A failed alternator might cost $400, but a transmission swap or an engine replacement can easily soar into the $3,000 to $5,000 range. This creates an immediate liquidity gap that most monthly budgets cannot absorb without planning. It is a sudden, sharp financial blow that catches most people off guard.

Finding a lender that accepts less-than-perfect credit scores is the primary goal for most people in this situation. When your credit score has been impacted by medical bills, student loans, or previous missed payments, traditional banking institutions often become inaccessible. You find yourself staring at a locked door when you need a way out.

This ranking focuses on speed, accessibility, and the reality of borrowing when your credit history isn’t your strongest asset. It is about getting back on the road without sinking further into a financial hole. We looked at how these lenders actually function when you are in a pinch.

  1. Manhattan Bank
  2. FastLendGo
  3. Addition Fi
  4. Minute Loan Center
  5. CreditNinja

How We Evaluated These Repair Financing Options

The selection process prioritized lenders that cater specifically to those facing unexpected automotive expenses. We looked for providers that offer quick turnaround times, which is critical when you need your vehicle for work or family obligations. Speed is often the difference between getting to a job and losing a paycheck.

If you are a delivery driver or a commuter with a long distance to travel, a three-day waiting period for funds might mean losing several shifts of income. This effectively increases the “true cost” of the loan. You aren’t just paying interest; you are paying for the time you spent without a car.

We also examined the breadth of loan products offered by each entity. A lender that provides various amounts, from small emergency sums to larger amounts, offers more flexibility for different repair scenarios. A simple brake pad replacement might only require a $300 quick loan.

Conversely, a blown head gasket might require $2,500. We looked for lenders that don’t force you into a massive loan if you only need a small fix, and those that can scale up for major structural repairs. The following comparison highlights the key features available for each provider based on their current service offerings.

Lender Name Loan Amounts Funding Speed Credit Requirements
Manhattan Bank See site See site See site
FastLendGo $500 – $5,000 See site Bad/Fair Credit
Addition Fi Up to $5,000 See site See site
Minute Loan Center See site Same-day Fair Credit
CreditNinja See site Same day* Bad Credit

The Best Lenders for Automotive Repairs

1. Manhattan Bank

Manhattan Bank – manhattanbank.com

Manhattan Bank operates as a traditional banking institution with the security of FDIC insurance. This provides a level of peace of mind that many specialized online lenders simply cannot match. For those who prefer working with a formal bank structure, this is a solid option for various personal loan needs.

Because they are a full-service bank, they offer a more structured approach to borrowing. While this might mean a slightly more thorough vetting process—often involving a review of your debt-to-income ratio and employment history—the stability of an FDIC-insured institution is a massive advantage for long-term financial health.

When applying with a traditional bank, you are typically looking for a “Personal Loan,” which is unsecured. This means you don’t have to put your vehicle up as collateral, which is a significant relief if you are already struggling with car-related expenses. You can keep your title in your hand.

However, because they prioritize stability, they may require a more established banking history or a steady stream of documented income via pay stubs or W-2s. They want to see that your income is as reliable as their vaults.

Pros:

  • FDIC-insured security
  • Established banking reputation
  • Offers personal loans for many occasions

Cons:

  • May have more rigorous application requirements than quick-cash lenders

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo specializes in being a partner for those who might struggle with traditional bank requirements. They offer a wide range of specialized products, including specific options for auto repair loans and even motorcycle loans. This makes them a versatile choice for various mechanical emergencies.

Instead of trying to fit a square peg into a round hole with a general-purpose loan, FastLendGo‘s specialized products are tailored to the reality of automotive ownership. They understand that a car isn’t just a luxury; it is often a tool for survival.

With loan amounts ranging from $500 up to $5,000, they cater to both small fixes and larger, more significant engine repairs. This range is particularly useful for tiered repair needs. You can address the immediate crisis without over-borrowing.

For instance, if your mechanic says, “You need a new fuel pump now, but you can wait six months on the suspension,” FastLendGo allows you to borrow exactly what is needed for the immediate crisis. Their focus on high-speed access makes them a strong contender for anyone in a time-sensitive situation.

Pros:

  • Specific auto repair loan options
  • Flexible loan amounts from $500 to $5,000
  • Designed for bad and fair credit

Cons:

  • Limited to specific states

3. Addition Fi

Addition Fi – additionfi.com

Addition Financial Credit Union offers a membership-based approach to personal banking. For those looking to build a long-term relationship with a financial institution, this is a standout choice. Credit unions are member-owned cooperatives, which often means they operate with a different philosophy than for-profit banks.

Their primary goal is to serve their members, which can translate to more personalized service and competitive terms. It feels less like a cold transaction and more like a community resource. They aren’t just looking at numbers on a screen; they are looking at people.

They offer competitive rates and a variety of loan products. While they are a broader credit union, their ability to help members “borrow smarter” makes them a reliable option for those who want to manage their debt responsibly while fixing their vehicle.

Because credit unions often have slightly more flexible underwriting criteria than large national banks, they may be more willing to look at the “why” behind a low credit score—such as a past medical emergency—rather than just the score itself. They see the human story behind the data.

Pros:

  • Credit union membership benefits
  • Competitive rates for members
  • Diverse range of financial products

Cons:

  • Requires membership to access full benefits

4. Minute Loan Center

Minute Loan Center – minuteloancenter.com

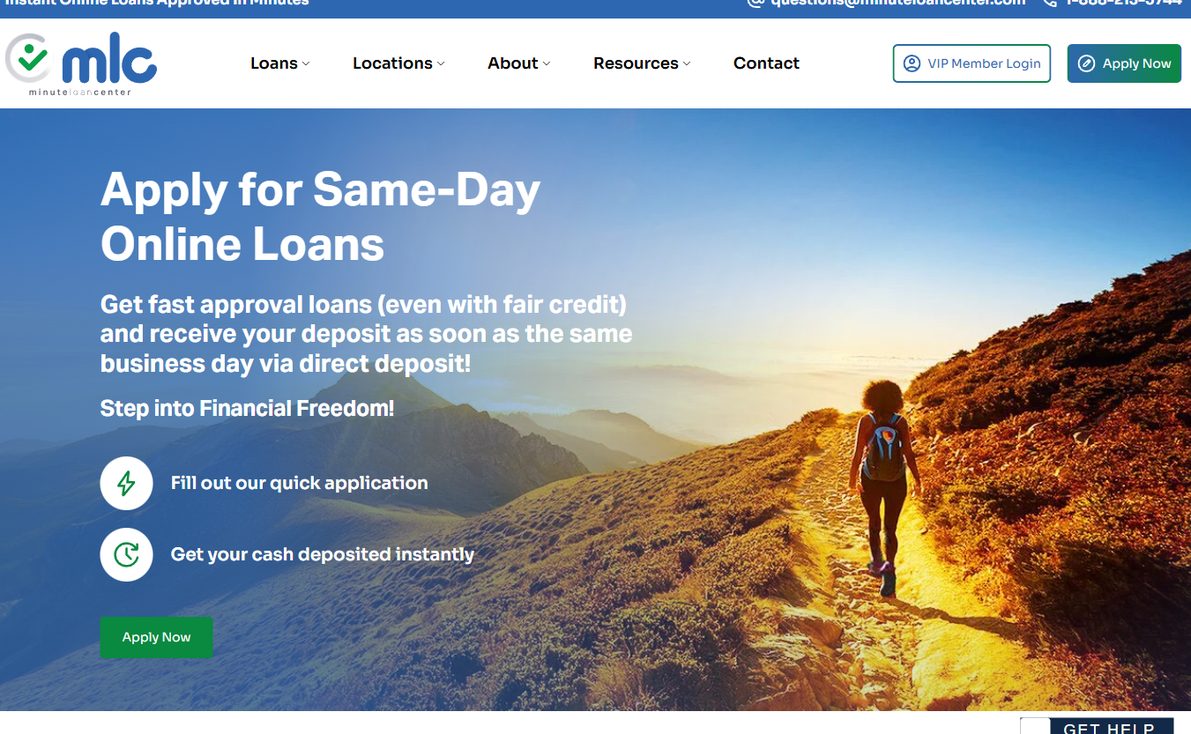
When the car is stuck in the shop and the clock is ticking, Minute Loan Center offers a rapid response. They focus heavily on the speed of the application and the immediacy of the funds. Their model is built for people who need cash to be deposited as soon as the same business day.

This is a vital feature for those living paycheck to paycheck, where a three-day delay in funds could mean a late fee on rent or a missed utility payment. In these moments, every hour feels like a lifetime. They aim to cut that waiting time down to almost nothing.

The platform is designed to be straightforward, aiming to help users step into financial freedom through quick approvals. The digital-first approach means you can often complete the entire process from your smartphone while waiting in the mechanic’s lobby.

This is ideal for the driver who cannot afford to miss a day of work because their vehicle is sidelined and they need to authorize the repair immediately to get it back on the road. They prioritize getting you back to work, which keeps your income flowing.

Pros:

  • Same-day deposit potential
  • Fast approval process
  • User-friendly online application

Cons:

  • Approval is dependent on fair credit status

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja acts as a bridge for those who find themselves unable to get approved by traditional lenders. Their system is designed to match users with loan options that fit their specific credit profile. It is a way to stop guessing and start knowing.

Rather than you spending hours applying to ten different lenders only to get ten rejections, CreditNinja uses a matching algorithm to point you toward the lenders most likely to approve your specific situation. It is a streamlined way to find a solution when other doors have closed.

The process is quick and simple, focusing on providing a fast decision. If you are in a pinch and need to know where you stand without a long, drawn-out waiting period, this is an efficient way to explore your options.

It acts as a powerful reconnaissance tool for anyone who is unsure of their eligibility in a high-pressure environment. It helps you narrow your search so you aren’t wasting energy on lenders that will simply say no.

Pros:

  • Same-day decision potential
  • Quick and simple online application
  • Targets those with bad credit

Cons:

  • Does not guarantee approval

Understanding the Total Cost of Borrowing

When you are in an emergency, it is easy to focus solely on the monthly payment, but this can be a dangerous trap. To truly understand your financial obligation, you must look at the Annual Percentage Rate (APR). This includes both the interest rate and any mandatory fees.

A loan with a “low” monthly payment might actually be more expensive over the long term if the interest rate is significantly higher than a standard bank loan. Don’t let a small number hide a large debt. Look at the grand total you will pay back by the end of the term.

Consider these three factors when reviewing a loan offer:

  • The Repayment Term: A 24-month loan will have much lower monthly payments than a 12-month loan, but you will pay significantly more in total interest over that extended period.
  • Origination Fees: Some lenders deduct a fee from the loan amount before you even receive it. If you need exactly $1,200 for a repair but the lender charges a $100 origination fee, you will only receive $1,100, leaving you short at the mechanic.
  • Prepayment Penalties: If you receive a bonus at work or a tax refund and want to pay off the car loan early to save on interest, some lenders charge a fee for doing so. Always check if “prepayment is without penalty.”

Smart Steps to Prepare for Your Loan Application

Securing a loan under pressure is difficult, but being prepared can increase your chances of approval and better terms. Even if you are applying for a high-speed loan, having your documentation ready can prevent delays that could leave you stranded without transport.

Follow these steps to streamline the process:

  1. Gather Documents: Have your most recent pay stubs, a government-issued ID, and your bank account details (for direct deposit) ready. If you are self-employed, have your last two years of tax returns on hand.
  2. Get a Written Estimate: Do not guess the amount you need. Ask your mechanic for a detailed, written estimate that includes parts and labor. Borrowing too little leads to more debt later; borrowing too much leads to unnecessary interest.
  3. Check Your Own Credit: While you may have bad credit, knowing your score helps you understand which lenders (like CreditNinja or FastLendGo) are your most viable targets.
  4. Verify Your Income: Lenders want to see that you have the ability to repay. Even if your credit is poor, a stable, documented income is your strongest asset during the underwriting process.

Navigating your borrowing options requires a balance of urgency and caution. Before signing any paperwork, it is vital to look at the total cost of the loan. Interest rates can vary wildly between a traditional bank and a specialized lender. Always ask for the total amount you will be paying back over the life of the loan, not just the monthly payment.

Another common pitfall is rushing into a high-interest loan just to solve an immediate problem. While speed is important, an expensive loan today can become a heavy burden tomorrow. Compare your options carefully and ensure the repayment schedule fits comfortably within your monthly budget.

If a monthly payment would mean you can’t afford groceries or gas, the loan is too large or the term is too long. You shouldn’t have to choose between fixing your car and feeding your family. Take a breath and look at the math one more time.

Finally, read the fine print regarding any fees. Some lenders charge origination fees or prepayment penalties that can catch you off guard. Taking ten minutes to read the terms can save you hundreds of dollars in the long run, ensuring your car repair doesn’t lead to a financial disaster. Your goal is to get back on the road, not to remain stuck in a cycle of high-interest debt.

Top 5 Lenders for Same Day Personal Loans in 2026

Same day personal loans

Top 5 Lenders for Same Day Personal Loans in 2026

Last updated: 2026-10-16

Life rarely waits for a convenient time to throw a curveball. Whether it is an unexpected car repair that leaves you stranded, an urgent medical bill, or a leaking roof that needs immediate attention, finding quick cash can feel like chasing a ghost in a crowded room. In these high-stress moments, the mental bandwidth required to handle complex financial systems often vanishes first.

This is why many people turn to same-day personal loans to bridge the gap between a sudden crisis and their next paycheck. Choosing a lender is about more than just who moves the fastest. If you prioritize speed above all else, you might find yourself trapped in a high-interest cycle that takes years to escape.

It is about finding a balance between speed, cost, and the long-term impact on your financial reputation. This ranking looks at the most reliable options currently available to help you handle these high-pressure moments without making a mess of your future. We have analyzed the top players in the market for 2026.

  1. JetzLoan
  2. Avant
  3. SoFi
  4. Discover
  5. CreditNinja

How the Top Lenders Were Evaluated

The selection process focused heavily on how fast money hits your account and how easy the application feels. Nobody wants to spend hours filling out paperwork or waiting on hold with a representative only to wait a week for a decision. We looked for lenders that offer digital-first experiences and rapid deposit timelines using modern banking technology.

Beyond speed, we looked at accessibility and transparency. We prioritized lenders that provide clear information regarding credit impacts and loan amounts. It is vital to know if a hard credit pull is required before you start clicking buttons, as this can affect your ability to secure a mortgage or an auto loan later.

A “soft pull” allows you to shop around for the best interest rate without a penalty. This is a critical distinction for anyone trying to maintain a healthy credit profile while seeking emergency funds. We also evaluated the friction within the application journey, such as whether a lender uses automated systems like Plaid to verify income instantly or requires manual pay stubs.

The goal was to identify lenders that respect your time as much as your money. We wanted to see who makes the process painless and who leaves you scrambling for documentation. The following table summarizes our findings across the top five candidates.

Lender Loan Amount Range Funding Speed Credit Impact Check
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
Avant $2,000 – $35,000 Fast decision See site
SoFi See site See site See site
Discover $2,500 – $40,000 As early as next business day No impact to credit score for pre-approval
CreditNinja See site As soon as the same day See site

Ranking of Best Lenders

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan connects borrowers with various top lenders in a matter of minutes. Rather than being a single bank, it functions as a marketplace. This is a significant advantage because it saves you the time of visiting ten different websites to see who will give you the best rate. Instead, you enter your data once, and the platform does the heavy lifting.

The process is remarkably streamlined, requiring less than two minutes to complete the initial form. This makes it a standout for anyone who needs to move quickly without a heavy administrative burden. For example, if you are at a mechanic’s shop and need to pay for a repair immediately to get your car back, the speed of JetzLoan is designed for that exact scenario.

The platform is built for those who might be nervous about their credit standing. Because they offer a way to check rates without a hard credit pull, you can explore your options without any fear of damaging your score. It is a low-pressure way to find significant funding without the “sticker shock” of seeing a credit score drop before you even know if you qualify.

Pros:

  • Funds can be deposited in as little as 24 hours.
  • No hard credit pull required for the initial rate check.
  • High customer rating of 4.7 stars.

Cons:

  • Acts as a marketplace rather than a direct lender.

2. Avant

Avant – avant.com

Avant focuses on providing flexible tools for people who are navigating complex financial journeys. They understand that “one size fits all” rarely works in lending. They offer solutions for various needs, including debt consolidation, emergency expenses, and home improvements. This versatility is helpful for someone trying to solve two problems at once.

You might find yourself needing to pay off a high-interest medical bill and a predatory payday loan in a single lump sum. Their application process is simple, utilizing a three-step method to get you from start to finish. This is ideal for someone who needs a quick decision to handle an unexpected life event.

They aim to provide clarity when you might be facing difficult financial questions. They often provide clear terms upfront so there is no confusion about what your monthly payment will look like. This transparency helps prevent any nasty surprises when the first bill arrives in your inbox.

Pros:

  • Simple, three-step application process.
  • Options for debt consolidation and emergency loans.
  • Flexible solutions for different financial goals.

Cons:

  • Specific eligibility requirements are not always immediately transparent.

3. SoFi

SoFi – sofi.com

SoFi is a massive player in the financial ecosystem, offering everything from banking and checking to investing and mortgages. For those who want a one-stop shop for their entire financial life, this is a powerhouse. They cater to a wide range of needs through digital, automated processes that feel much more like a modern tech app than a traditional bank.

While they are known for more traditional long-term financial products, their digital-first approach allows for much faster movement than old-school banks. They are a great option for borrowers who value a high-tech, integrated experience across all their various money management needs. If you already have a high credit score, SoFi is often the gold standard.

They offer premium rates with zero paperwork for those who qualify. The experience is incredibly fluid, making it easy to manage your finances from your phone. It is a sophisticated option for users who want their lending to match their digital lifestyle.

Pros:

  • Comprehensive financial suite including investing and banking.
  • Highly digital and automated application process.
  • Reputable brand with extensive financial tools.

Cons:

  • May require higher credit standards for the best terms.

4. Discover

Discover – discover.com

Discover brings a sense of traditional stability to the online lending world. They offer a wide range of products, including credit cards and personal loans, with a focus on customer service and security. It is a solid choice for someone who wants a well-established name behind their loan.

You might want to know that if you have a question, there is a massive infrastructure of customer support ready to assist them. The platform is particularly useful for those who want to “check before they commit.” You can see if you are pre-approved for certain products with no impact to your credit score.

This allows for a cautious approach to borrowing in an uncertain economic climate. It is a “try before you buy” model that removes the anxiety of the unknown. If you prefer a lender that feels like a pillar of the industry, Discover is a reliable bet.

Pros:

  • Pre-approval checks do not impact credit scores.
  • Wide range of loan amounts available.
  • Highly rated customer service and security.

Cons:

  • Funding may take until the next business day rather than the same day.

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja is a go-to option for those who might find traditional banks a bit too stingy. They specialize in helping people who may not qualify for standard loans, offering a path to finding solutions for unexpected life expenses. Their application is designed to be quick and simple, focusing on your specific profile.

The standout feature here is the potential for same-day money. If you are approved and sign for your loan, the funds may be deposited directly into your account as early as the same day. This is a lifesaver when a deadline is looming, such as an eviction notice or a utility shut-off warning.

It is designed for high-stakes situations where every hour counts. While you might pay more for this speed, the ability to resolve a crisis immediately is worth a lot to many people. It is a specialized tool for those in urgent need.

Pros:

  • Potential for same-day funding upon signing.
  • Designed for those who struggle with traditional loan approvals.
  • Quick and easy online application process.

Cons:

  • Interest rates can be higher for those with less ideal credit.

The Step-by-Step Process of Securing a Quick Loan

To ensure you get the best possible outcome, you should approach the application process with a specific workflow. Following these steps can prevent common delays that turn a “same-day” loan into a “three-day” headache.

Step 1: Gather Your Documentation in Advance. Even with automated systems, you will likely need to provide your Social Security Number, your monthly gross income, and your primary banking details. Having a digital copy of your most recent pay stub or a bank statement ready to upload can prevent the application from stalling in the “pending verification” stage.

Step 2: Use a Soft Credit Pull First. Always look for the “check your rate” option. This allows you to see the estimated APR and monthly payment without any risk to your credit score. If the rate is significantly higher than you can afford, you can walk away without any lasting financial damage.

Step 3: Compare the APR, Not Just the Monthly Payment. This is where many borrowers make a mistake. A lender might offer a very low monthly payment, but if that is because they have stretched the loan term out to five years, you will end up paying thousands more in interest. Always look at the total cost of the loan over its entire lifespan.

Step 4: Verify the Funding Method. If you need money today, ensure you have a checking account that supports “Real-Time Payments” or “Instant ACH.” Some lenders can send money instantly, but if your bank only processes transfers overnight, you won’t see that cash until the next business morning regardless of how fast the lender acts.

Avoiding Common Pitfalls When Borrowing

The first mistake many people make is rushing into the first offer they see without looking at the fine print. While speed is the primary goal, the cost of that speed can be high. Always check the total cost of the loan to ensure it is manageable. Specifically, look for “origination fees.”
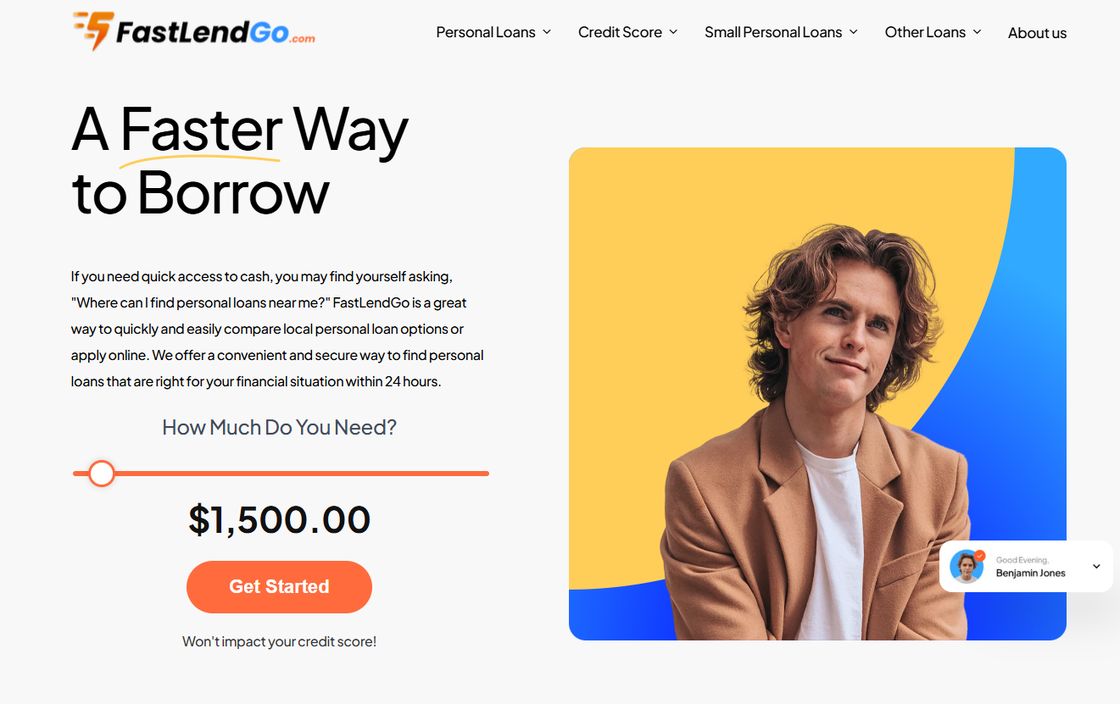
If you borrow $1,000 but the lender takes a $50 origination fee, you only receive $950, but you still owe interest on the full $1,000. Another trap is forgetting to compare different types of credit. Sometimes, a credit card with a low interest rate might actually be cheaper than a quick personal loan for a small amount of money.

Take a moment to breathe and evaluate your total debt-to-income ratio before signing. If your monthly debt payments already consume a large portion of your income, adding another loan could lead to a cycle of borrowing just to pay off previous debts. Avoid the temptation to borrow more than you absolutely need.

Every dollar borrowed is a dollar that must be repaid with interest. Use these tools as a bridge to get you from one stable point to another, not as a permanent lifestyle adjustment. A loan should be a tool for resolution, not a source of new, ongoing stress.

Top 6 Lenders for Emergency Loans for Bad Credit in 2026

Emergency loans for bad credit

Top 6 Lenders for Emergency Loans for Bad Credit in 2026

Last updated: 2026-10-16

Life has a way of throwing a wrench into even the best-laid plans. A sudden transmission failure leaves you stranded on the highway, an urgent root canal brings an unexpected dental bill, or an HVAC breakdown strikes during a heatwave. In those moments, the need for immediate cash feels overwhelming. When your credit score isn’t exactly a glowing endorsement—maybe due to past medical debt or a period of unemployment—finding a lender feels like searching for a needle in a haystack.

This ranking focuses on speed, accessibility, and transparency for people facing urgent financial hurdles. Finding a lender that accepts less-than-perfect credit is only half the battle. The real challenge is ensuring the terms are manageable and the funds arrive before the crisis peaks. We analyzed several providers to see who stands out in this high-stakes market, looking at everything from digital application friction to the actual speed of capital deployment.

  1. Minute Loan Center
  2. FastLendGo
  3. Avant
  4. World Finance
  5. CreditNinja
  6. Reprise

How These Emergency Lenders Were Evaluated

Selecting the right lender requires looking past the flashy advertisements and marketing slogans. The evaluation process focused on how quickly funds could actually reach a borrower’s bank account after approval. In a true emergency, a three-day waiting period is often the difference between a solved problem and a mounting disaster. If you need to pay a mechanic to get to work on Monday morning, a lender that promises funds by Thursday is effectively useless. Speed is the primary metric of value here.

Beyond speed, the criteria included the ease of the application process and the variety of credit profiles accepted. A lender that requires a mountain of paperwork, physical visits to a branch, or multiple days of manual verification might be too slow for a midnight crisis. We also looked for providers that offer clear pathways for those with bad credit, ensuring no hidden surprises lurk in the fine print, such as predatory prepayment penalties or excessive origination fees that balloon the total cost of borrowing.

Lender Name Speed of Funding Max Loan Amount Credit Requirements
Minute Loan Center Same-Day See site Fair credit accepted
FastLendGo See site $5,000 Bad/Fair/Good
Avant See site See site Less than perfect credit
World Finance See site See site See site
CreditNinja Same-Day (with conditions) See site Bad credit okay
Reprise See site See site See site

Ranked Emergency Loan Providers

1. Minute Loan Center

Minute Loan Center – minuteloancenter.com

When the clock is ticking, Minute Loan Center steps into the ring with a focus on velocity. They specialize in same-day and instant online loans, aiming to get deposits into your account via direct deposit as soon as the business day begins. This makes them a heavy hitter for anyone staring down a deadline, such as a utility shut-off notice or a rent payment that is due by the end of the business day.

They cater specifically to those who might struggle with traditional bank requirements, offering approval even for those with fair credit. Because they have been around for over two decades, they have established a reputation for stability. In an era of fly-by-night fintech startups, having a provider that has weathered multiple economic cycles provides an extra layer of peace of mind. It is a solid choice for quick, digital-first relief when you cannot afford to wait for a manual underwriting process.

Pros:

  • Very fast same-day direct deposit.
  • No hidden fees or credit pulls mentioned.
  • Experienced provider with decades of service.

Cons:

  • Primarily focuses on a specific niche of rapid funding.

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a versatile partner for various personal financing needs, ranging from small $500 loans to larger $5,000 requests. They seem to understand that a car repair requires a different approach than a roof repair. For instance, if you need a small amount to cover a tire replacement, a large installment loan might be overkill. Conversely, if you are facing a major home repair, a tiny microloan won’t cut it.

Their platform is designed to help users compare local options quickly to find that middle ground. (fastlendgo.com) The service is built for those who need to skip the long lines and the endless wait times associated with brick-and-mortar lenders. Whether you have bad credit or are just starting your journey with no credit history, they offer a path forward. It is a flexible option for those who need specific amounts for specific crises, allowing for a tailored approach to borrowing that matches the scale of the emergency at hand.

Pros:

  • Wide range of loan amounts from $500 to $5,000.
  • Covers various needs like auto or dental financing.
  • User-friendly comparison interface.

Cons:

  • The comparison model may lead to multiple offers.

3. Avant

Avant – avant.com

Avant approaches personal finance with a focus on long-term movement rather than just quick fixes. While they handle emergency loans, they also offer tools for debt consolidation and credit cards. This makes them a useful option if your emergency is actually part of a larger financial puzzle. For example, if you are taking a loan to cover a medical bill, Avant might also help you restructure your existing high-interest credit card debt to make your monthly budget more sustainable in the long run.

They are particularly welcoming to those with less than perfect credit, providing a bridge to help you move financially forward. Instead of just handing over cash, they aim to provide solutions that fit into your specific life journey. It is a more holistic approach to borrowing that prioritizes the borrower’s future stability rather than just the immediate transaction. It is ideal for the borrower who wants to solve a current crisis while simultaneously improving their credit standing.

Pros:

  • Supports debt consolidation alongside emergency needs.
  • Tailored solutions for different financial stages.
  • Strong focus on moving a borrower forward.

Cons:

  • May have stricter qualifying criteria than specialized lenders.

4. World Finance

World Finance – worldfinance.com

World Finance is a massive entity in the financial landscape, offering a broad spectrum of banking and investment services. While their focus often leans toward more complex financial structures, they maintain a presence in the retail banking space. This provides a level of professional scale that smaller, online-only lenders lack. For many, there is a psychological comfort in dealing with a large-scale institution rather than an unproven app.

For a borrower in a pinch, they represent a more institutional approach to money management. They are a significant player in the global and retail markets, making them a stable entity in the financial ecosystem. It is a choice for those who want a more traditional, large-scale provider and who may prefer the ability to engage with a provider that has a significant, established footprint in the financial sector.

Pros:

  • Highly established and large-scale institution.
  • Broad range of financial services available.
  • Deep expertise in various banking sectors.

Cons:

  • May feel less specialized for a quick, small-dollar emergency.

5. CreditNinja

CreditNinja – creditninja.com

CreditNinja is built for the “life happens” moments when traditional banks turn you away. Their application process is designed to be quick and simple, requiring only basic information to see if you qualify. This “soft inquiry” style approach is designed to protect your credit score while you are just testing the waters. It is a streamlined approach for when you simply don’t have time to waste on lengthy applications that might lead to a rejection.

If you are approved, you can potentially see your money deposited the same day. However, there is a catch: you must apply and be approved by 10:30 a.m. on a business day to catch that same-day window. This requires a bit of proactive planning even in an emergency. If you wait until 4:00 p.m. to check your options, you might be looking at a delay that pushes your funds into the next business day, potentially missing your deadline.

Pros:

  • Extremely simple and fast online application.
  • Potentially very fast same-day funding.
  • Designed specifically for those denied by traditional banks.

Cons:

  • Strict morning deadline for same-day funding.

6. Reprise

Reprise – reprise.com

Reprise operates in a slightly different lane, functioning as an enterprise demo creation platform. While they offer sophisticated AI toolset and data injection for agents, they are not a traditional consumer lender for personal emergency cash. Their focus is on helping businesses build powerful product tours for their software or services.

They provide incredible capabilities for capturing screens and creating high-fidelity demos that look like real user sessions. If your “emergency” is actually a business need for high-end presentation tools to close a major sales deal, they are a powerhouse. However, for someone needing cash for a broken water heater or a car repair, they are not the right tool. It is important to ensure you are applying to a lender and not a business software provider.

Pros:

  • Advanced AI toolset for demo creation.
  • High-quality data injection for professional presentations.
  • Excellent for enterprise-level product tours.

Cons:

  • Not a consumer loan provider for personal emergencies.

Essential Steps for Securing an Emergency Loan

Navigating the world of rapid lending requires a strategic approach to ensure you don’t exacerbate your financial situation. Follow these steps to maximize your chances of success and minimize your long-term debt burden:

  1. Audit Your Need: Before applying, calculate the exact amount required. If a repair is estimated at $800, don’t borrow $1,200 just because the lender offers it. The interest on that extra $400 will compound quickly.
  2. Verify the “Total Cost of Credit”: Don’t just look at the monthly payment. Look at the total amount you will have paid back by the end of the term. A low monthly payment often means a much longer term and a significantly higher total cost.
  3. Check for Hidden Fees: Look specifically for “origination fees” (charged upfront), “processing fees,” and most importantly, “late payment fees.” In an emergency, your schedule might be chaotic; you need to know the penalty if a payment is a day late.
  4. Confirm the Funding Method: Not all “same-day” loans are created equal. Some require you to visit a physical location, while others use ACH transfers. For true speed, ensure the lender supports instant direct deposit to your existing checking account.

How to Navigate Emergency Borrowing

The most common mistake is rushing into the first offer you see without checking the details. Even in a panic, take a breath and look at the total cost of the loan. A quick fix can become a long-term headache if the interest rates are not clearly understood before you sign. Interest rates for high-speed, bad-credit loans are naturally higher than traditional personal loans, so the speed comes at a premium price.

Avoid the temptation to borrow more than you absolutely need to resolve the immediate crisis. It is easy to think, “If I’m borrowing, I might as well get extra,” but that extra cash comes with extra cost. Stay disciplined, compare the options, and choose the one that gets you through the storm without drowning you later. Use the emergency as a stepping stone to stability, not as a permanent fixture of your monthly budget.

Top 6 Lenders for a Personal Loan with a Co-Signer in 2026

Personal loan with co signer

Top 6 Lenders for a Personal Loan with a Co-Signer in 2026

Last updated: 2026-10-16

Trying to find a lender when your credit score is lagging can feel like walking through a thick fog without a map. Bringing in a co-signer often acts as a lighthouse, helping you find better rates and a higher chance of approval. Just remember, this is a massive commitment for everyone signing the paperwork.

This list highlights lenders that offer flexibility for anyone needing a second pair of hands to back their debt. You might be looking to roll several bills into one or fix a leaky roof. Knowing which lenders are willing to play ball is a big part of staying financially healthy.

  1. OneMain Financial
  2. JetzLoan
  3. Reprise
  4. Prosper
  5. LendingPoint
  6. Acorn Finance

How These Lending Options Were Evaluated

We picked lenders that show a willingness to work with various credit profiles. A co-signer with a FICO score around 670 or higher can often unlock much better terms than a borrower could find on their own. We looked for companies that keep their processes transparent and get funds out quickly.

Speed and ease of use were major factors in our scoring. We prioritized companies that let you check rates without a hard credit pull, since you don’t want to tank your score just to see your options. This list reflects a mix of old-school stability and fast, digital-first speed for the 2026 market.

Lender Name Loan Amounts Funding Speed Credit Impact for Check Terms/Details
OneMain Financial $1,500 – $30,000 As soon as 1 hour No impact 24-60 months
JetzLoan $500 – $35,000 As little as 24 hours No impact Up to $50k max
Reprise see site see site see site AI Demo Platform
Prosper $2,000 – $50,000 Fast No impact Up to 6-year terms
LendingPoint $1,000 – $36,500 see site No impact see site
Acorn Finance see site Just now No impact Home Improvement Focus

Top Ranked Lenders for Co-Signed Borrowing

1. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a heavy hitter in the personal lending world. They are a great fit for people who might need a little extra help because of less-than-perfect credit. By letting you add a co-signer, they help turn a potential “no” into a “yes” for many applicants.

The speed they offer is impressive for a traditional lender. You can see your options in five minutes and potentially see funds hit your account just an hour after signing. That is a total lifesaver when you are facing an urgent situation and time is running out.

With fixed monthly payments and terms from 24 to 60 months, you know exactly what to expect. Having a real person you can call or visit at one of their 1,300 branches provides a safety net that purely digital apps often miss.

Pros:

  • Very fast funding, potentially within an hour.
  • Large branch network for in-person support.
  • No credit score impact when checking offers.

Cons:

  • Interest rates can be high for those with poor credit.

2. JetzLoan

JetzLoan – jetzloan.com

JetzLoan works like a high-speed connector in our digital age. They don’t make you jump through endless hoops. Instead, they try to connect you with top lenders in just a few minutes. It is a streamlined experience built for a busy life. (jetzloan.com)

The whole platform is built for speed. They claim funds can land in your account in as little as 24 hours, which makes them a top choice if you are dealing with a sudden financial hurdle. The interface is simple, so the application feels like a quick task rather than a chore.

Since they focus on bad credit and debt consolidation, they serve a crowd that big banks often ignore. They promise a process that is relatively stress-free, focusing on getting you cash without the usual headache.

Pros:

  • Extremely quick 2-minute application process.
  • No hard credit pull to check rates.
  • High customer satisfaction rating.

Cons:

  • The platform is a connector, not the direct lender.

3. Reprise

Reprise – reprise.com

Reprise is a bit of an outlier on this list because they occupy a different niche entirely. They are an AI toolset for creating enterprise demos. While they don’t give out personal consumer loans, they are a big deal for professionals working in tech.

Their platform lets agents build high-quality, data-driven demos using AI. It helps sales teams show off their products using realistic data and smooth transitions. It is a tool meant for boosting productivity, not for paying off personal debt.

If you want to boost your company’s sales capabilities, this is a powerhouse. However, if you are looking for a co-signed loan to cover your bills, you will find their services totally irrelevant to your needs.

Pros:

  • Powerful AI-driven demo creation tools.
  • Seamless data injection for product tours.
  • Helps sales agents become much more capable.

Cons:

  • Not a personal loan provider for consumers.

4. Prosper

Prosper – prosper.com

Prosper is a well-known name in the peer-to-peer lending world. They offer a flexible approach, with loan amounts from $2,000 up to $50,000. Their whole setup is based on connecting individual lenders with borrowers who need a helping hand.

They recently added 6-year terms to their lineup, which gives you more breathing room for monthly payments. This kind of flexibility is a godsend if you are trying to manage your cash flow while chipping away at significant debt.

Prosper gets high marks for ease of use. You can see your rates in about a minute. They also offer a variety of other products like credit cards and investing options, making them a one-stop shop for many users.

Pros:

  • Longer 6-year terms available for more flexibility.
  • Quick rate checks with no impact on credit.
  • Strong reputation in the peer-to-peer space.

Cons:

  • Peer-to-peer models can sometimes have variable availability.

5. LendingPoint

LendingPoint – lendingpoint.com

LendingPoint handles a variety of life events, from unexpected medical bills to home improvements. They offer a wide range of amounts, starting at $1,000 and going up to $36,500. This versatility makes them a good fit for many different situations.

The platform is designed to make money simple. You can check your rate without it touching your credit score, which is vital when you are shopping around for the best deal. You want to compare options without the penalty of a hard pull.

They cover everything from debt consolidation to wedding financing. This range, combined with how they handle different credit profiles, makes them a reliable option for many households.

Pros:

  • Wide range of loan amounts to suit different needs.
  • No credit score impact when checking rates.
  • Covers many different personal loan purposes.

Cons:

  • Terms and rates are not always explicitly listed upfront.

6. Acorn Finance

Acorn Finance – acornfinance.com

Acorn Finance takes a specialized path by focusing heavily on home improvement. They act as a marketplace that links borrowers with contractors and financing options specifically for projects like kitchen remodels or pool installs.

They are particularly useful if you need a large sum for a major renovation. Their system is fast; some people get offers minutes after applying via email or SMS. It is a very modern way to handle contractor financing.

Whether your credit is good or bad, Acorn Finance tries to find personalized rates. They use a “zero dealer fee” model, which can save you a lot of money when you are dealing with expensive home projects.

Pros:

  • Specialized in home improvement and contractor financing.
  • Extremely fast response times for offers.
  • No dealer fees for the borrower.

Cons:

  • Highly specialized, which might not suit non-home projects.

Navigating the Co-Signer Process

Picking a lender is only half the battle; you also have to pick the right co-signer. This person should have a strong FICO score and a steady income. They are essentially telling the lender, “If this person fails, I will pay the debt.” That is a massive weight to carry, and it can hurt their own credit if things go sideways.

Don’t make the mistake of rushing into a loan just because a lender accepts a co-signer. You must sit down with that person and talk through a real repayment plan. You don’t want a financial emergency to turn into a massive fight with a family member. Open communication is your most important tool here.

Finally, keep a close eye on the total cost of the loan. A lower interest rate sounds great, but if the term is too long, you might end up paying much more in total interest over time. Do the math before you sign anything to ensure the loan stays a help rather than a burden.

Top 5 Lenders for First Time Personal Loans With No Credit History in 2026

First time personal loans no credit history

Top 5 Lenders for First Time Personal Loans With No Credit History in 2026

Last updated: 2026-10-16

Walking into a bank to ask for money when you have no credit history feels like trying to find your way through a pitch-black room without a flashlight. If you have never owned a credit card or financed a car, traditional banks might treat you like a ghost. It is a frustrating cycle where you need a history of credit just to prove you are worthy of it.

This financial Catch-22 leaves many people in limbo. Young professionals, recent immigrants, and those trying to recover from a past financial setback often find themselves locked out of the very tools needed to build a stable life. It can feel like the system is designed to keep you on the sidelines.

Fortunately, the way lenders look at your wallet has changed this year. Lenders are moving away from staring at a single FICO number to decide your fate. Instead, they are looking at your actual income, how steady your job is, and your overall financial habits. Your utility bills and rent history now carry much more weight than they did five years ago.

By looking at the whole picture rather than just one score, lenders can extend credit to millions of people who were previously considered unscorable. This shift toward alternative data means your paycheck and consistent bills are your new best friends in the eyes of a loan officer.

  1. JetzLoan
  2. Discover
  3. OppLoans
  4. OneMain Financial
  5. Coastline Credit Union

How These Lenders Were Evaluated for New Borrowers

When we built this ranking, our main goal was finding accessibility for people without a credit footprint. We searched for lenders that offer “soft pulls” or pre-qualification steps. This is a vital distinction. A soft pull lets you see your potential terms without any risk to your score. You can “window shop” for rates without any penalty.
A “hard inquiry” is different. That happens when a lender digs deep into your credit report to make a final decision, and it can shave points off your FICO score. By prioritizing companies that use soft pulls during the initial phase, we tried to protect your growing credit history from unnecessary damage.
Speed and transparency were the next big things we checked. A lender that hides fees in the fine print or waits two weeks to deposit your money is useless if you are facing an emergency. If a car transmission fails or a medical bill arrives, you need cash, not excuses. We looked for companies that provide clear amounts, quick funding, and easy ways to talk to a human.

We also insisted on lenders that clearly state their APR. This number is the real truth because it includes both the interest rate and any mandatory fees. Knowing the APR gives you a genuine look at how much this loan will actually cost you over time.

We also looked at whether a loan acts as a tool for growth or a trap for debt. We favored lenders that offer predictable monthly payments. Avoid anyone using predatory interest structures that can lead to a debt spiral. We studied the difference between simple interest and compounding interest, as the latter can make your debt balloon much faster than you expect.
Lender Name Loan Amounts Funding Speed Credit Impact Check Minimum/Max Terms
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull see site
Discover $2,500 – $40,000 As early as next business day No impact to credit score see site
OppLoans see site Same-day funding available Does not affect FICO score see site
OneMain Financial $1,500 – $30,000 As soon as 1 hour after signing No credit score impact 24-60 months
Coastline Credit Union see site see site see site see site

The 2026 Ranking of Top Lenders

1. JetzLoan

JetzLoan – jetzloan.com

JetzLoan helps people who are trying to navigate the tricky waters of a thin credit file. By connecting you with various top lenders, they make the search much simpler. It is a great choice if you need cash fast for an unexpected car repair or to consolidate some urgent debt.

Instead of wasting hours applying to ten different places and risking ten different hard inquiries, JetzLoan gathers your options into one single, streamlined experience. This saves you time and protects your score while you are still figuring out your options.

The application is quick, usually taking about two minutes. Since they use a “no hard credit pull” model during the start, you can explore without any fear. You can see if you qualify for up to $35,000 without any pressure. This is perfect for first-time borrowers who are still learning how to read loan offers and don’t want to mess up their standing before they truly understand the fine print.

Pros:

  • Fast funding within 24 hours
  • Up to $35,000 available
  • Simple, two-minute application
  • No impact to credit score during check

Cons:

  • Requires a simple form to start

2. Discover

Discover – discover.com

Discover is a massive name in banking, offering the kind of stability many new borrowers want. Their personal loans are built for people looking for a long-term financial partner, not just a quick check. With rates starting as low as 6.99% APR, they provide a real path to growth.

If you are moving from “no credit” to “rebuilding,” Discover offers a structured environment that rewards you for paying on time. They have a very clear pre-approval process that won’t touch your credit score. If you get the green light, the money can be in your account as early as the next business day.

They are a reliable choice for anyone with steady income who wants to work with a major institution. Because they are so large, their digital tools are excellent. You can manage your payments, check statements, and track your progress through a very smooth mobile app.

Pros:

  • High loan limits up to $40,000
  • Competitive APR starting at 6.99%
  • Fast funding by next business day
  • Highly reputable and FDIC-insured

Cons:

  • May have stricter income requirements

3. OppLoans

OppLoans – opploans.com

OppLoans is designed for the person who has heard “no” from every big bank in town. They look past the traditional FICO score to find reasons to say “yes” to you. This makes them a vital resource for those just starting out or those who have faced a recent hiccup, like a medical emergency or a temporary job gap.

They care about your current ability to pay, often looking at your bank account activity rather than just a static number from a bureau. The platform is built for speed, and you might even see same-day funding. It is a much safer way to get cash than the payday loan industry.

Payday loans are notorious for astronomical interest rates that can exceed 400% APR, which often traps people in a cycle of debt. OppLoans provides a structured alternative. You get a way to manage your needs without the predatory terms and hidden fees that make other quick-cash options so dangerous.

Pros:

  • Same-day funding potential
  • Does not affect FICO score
  • Designed for those turned down elsewhere
  • No hidden fees

Cons:

  • Interest rates may be higher than traditional banks

4. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial offers a mix of digital ease and human connection. If you would rather talk to a real person than a chatbot, their 1,300 branches are a huge benefit. This is perfect if you want to sit down with someone to explain a specific situation, like a one-time change in your income.

That human element can be the difference between a denial and an approval. They offer flexible terms from 24 to 60 months, so you can tailor the monthly payment to fit your budget. With loans starting at $1,500, they work for everything from small home fixes to larger debt consolidation.

The speed is impressive too. You could have funds available just one hour after signing. It is rare to find that kind of speed from a lender that has such a large physical presence across the country.

Pros:

  • Extensive branch network for in-person help
  • Fast funding (1 hour post-signing)
  • Flexible terms up to 60 months
  • No obligation pre-check

Cons:

  • Interest rates can vary significantly

5. Coastline Credit Union

Coastline Credit Union – coastlinecu.com

Credit unions are often the best-kept secret for people new to borrowing. Coastline Credit Union uses a member-focused model, which usually leads to more personalized service. Unlike big banks that exist to satisfy shareholders and drive quarterly profits, credit unions are cooperatives owned by their members.

Their primary goal is to serve the community, which often results in more lenient underwriting for local residents. While you might have to meet certain membership requirements—like living in a specific county or working in a certain field—the perks are often worth it. They offer various loan solutions and digital tools to help you manage your money.

It is a “slow and steady” way to build a financial foundation. The lender is actually invested in your long-term success, not just how much interest they can squeeze out of you this month.

Pros:

  • Member-centric service model
  • Diverse range of financial solutions
  • Potential for better long-term rates

Cons:

  • Membership requirements may apply

Understanding Interest Rates: APR vs. Simple Interest

When you look at loan offers, you will see two different types of numbers. You need to know the difference to avoid getting burned. The first is the Simple Interest Rate, which is just the basic cost of borrowing the principal. But that does not tell the whole story of what you will actually pay.

The second, and much more important, number is the Annual Percentage Rate (APR). The APR includes the interest rate plus any other costs needed to get the loan, like origination fees or documentation fees. This is the number that actually matters for your wallet.

For instance, if you take a $5,000 loan at a 10% interest rate, but the lender charges a $500 “processing fee,” your APR is much higher than 10%. Always use the APR when comparing two different lenders. If Lender A has a 7% rate but high fees, and Lender B has an 8% rate with no fees, Lender B is actually the cheaper choice. Do not let a low “headline” interest rate distract you from the total cost shown in the APR.

The Golden Rules of Borrowing for Beginners

If you are new to this, stick to these three rules to keep your financial health intact:

  1. The 30% Rule for Monthly Payments: Never agree to a loan where the monthly payment is more than 30% of your take-home pay. If you make $3,000 a month, your total debt payments should stay well below that. If a loan forces you to spend half your check on debt, you are in a danger zone for default.
  2. Avoid “Term Stretching”: It is tempting to take a 60-month loan instead of a 36-month one because the monthly payment is lower. However, the longer the term, the more interest you pay. Over 60 months, you might end up paying back nearly double what you borrowed. If you can afford the higher payment, take the shorter term.
  3. Verify the “Total Cost of Loan”: Before you sign anything, ask: “What is the total amount I will have paid back by the end of this term?” That number is the truth. If you borrow $2,000 and the total repayment is $3,500, you just paid $1,500 to use that money. Knowing this prevents shock when you see your bank statements later.

How to Navigate Your First Loan Application

Before you hit “apply,” have a clear plan. Borrowing money is a commitment to a repayment schedule, not just a way to get quick cash. Calculate exactly what you need so you don’t over-borrow. It is much easier to pay off a small loan than a massive one. Many people borrow the maximum amount just to have a “safety net,” but they end up paying interest on money they never even needed.

Don’t just look at the monthly payment. Look at the APR and the total amount you will pay over the life of the loan. A low monthly payment often means a much longer term, which can cost you thousands in interest. Use an online calculator to see how changing your payment by even $25 a month can save you hundreds of dollars in the long run.

Gather your documents before you start. Even if a lender says they don’t need a hard credit check, you will eventually need to prove your identity and income to finish the contract. Have your recent pay stubs, bank statements, and ID ready to go. If you are consolidating debt, have those creditor statements ready too; some lenders can pay them directly, which makes the whole process much smoother.